Business
Ghana on Track for Exponential Productivity and Growth with Novel ’24‑Hour Authority’ Proposal

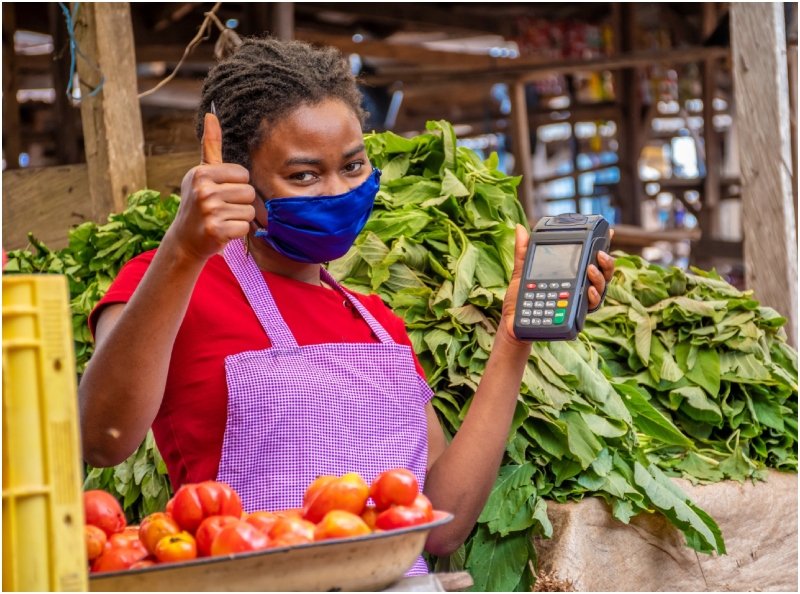
President John Dramani Mahama has announced that the government will soon establish a 24‑Hour Authority to drive the implementation of Ghana’s flagship 24‑hour economy policy.
The flagship policy featured prominently in Mahama’s 2024 election campaign promise and now is his administration’s strategic move to boosting productivity, expanding trade, and fostering broad‑based economic transformation.
Addressing officials and stakeholders during a visit to the Ghana Publishing Company, President Mahama said a special committee has completed its review of the 24‑hour economy framework, and its report is expected to be laid before Parliament to enable the legal creation of the Authority. The new body will be central to the registration of participating businesses, defining incentives, and coordinating implementation across sectors.
“Once established, the 24‑Hour Authority will be the fulcrum for operationalizing our continuous‑production model and ensuring that Ghana remains competitive in a 24/7 global marketplace,” the President said.
Policy Aims and Strategic Focus
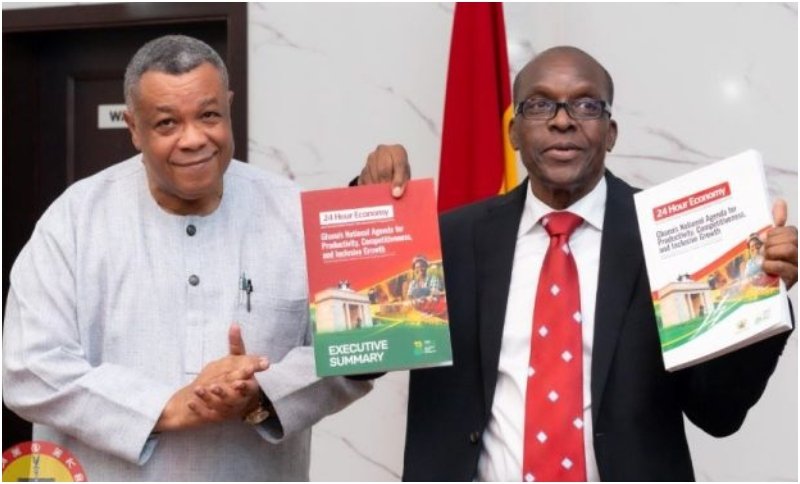
The 24‑hour economy initiative represents one of the most ambitious economic policies of the Mahama administration, designed to transition Ghana from a traditional daytime economic model to a round‑the‑clock system that maximizes the utilization of infrastructure, human capital, and industrial capacity.
Under the initiative, key public institutions and services — including ports, regulatory bodies, and service agencies — are already adopting extended operating hours. The policy also envisages incentivizing private sector participation through tax benefits, cheaper utility rates, and business support frameworks once the Authority commences operations.
Economic Implications and Benefits
Experts and government officials argue that the institutionalizing the 24‑hour economy could have far‑reaching implications for Ghana’s economic trajectory:
- Increased Productivity: Continuous operations in manufacturing, logistics and services can enhance output and reduce delays associated with traditional work‑hour constraints.
- Trade and Exports: Ghana’s major seaports, including Tema and Takoradi, have already begun 24‑hour operations to expedite cargo handling, improve turnaround times, and enhance international competitiveness.
- Job Creation: The shift to multi‑shift systems is expected to generate employment opportunities across sectors, particularly for youth and women, as firms expand operations to cover all hours.
- Service Delivery: Extended hours for services such as passport processing and public licensing could significantly improve access for citizens and businesses alike.
Economists note that the Authority’s success will depend on effective coordination with private sector partners, robust infrastructure support (especially energy and logistics), and regulatory frameworks that protect worker rights while encouraging investment.
Context in Broader Economic Strategy
The creation of the 24‑Hour Authority fits within a larger national agenda focused on resetting Ghana’s economic model toward higher productivity, export‑driven growth, and inclusive employment.
It complements other initiatives such as the Volta Economic Corridor, skills development programs, and expanded financing mechanisms to support industrialization.
Ghana, since Mahama’s return to the presidency, has been on an ascendant path towards macroeconomic recovery after challenges in the recent past. Hence, keep the pace and deepen the country’s participation in global value chains, the 24‑hour economy — and the proposed Authority that will be tasked with overseeing it — must become a defining feature of the country’s long‑term economic strategy.






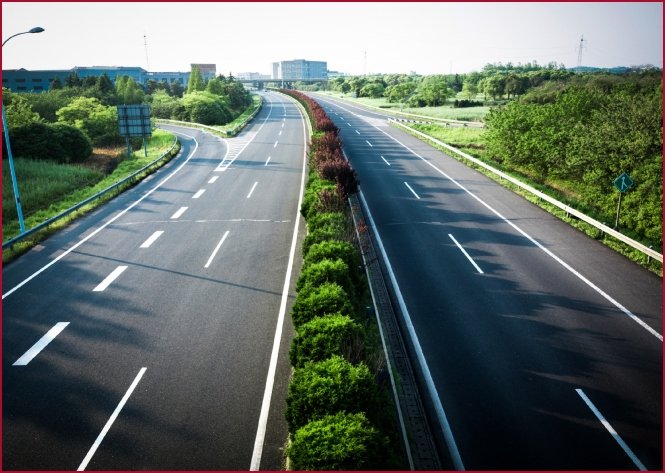
In a bold departure from Ghana’s traditional reliance on external debt, the government has announced that the entire $2 billion needed to finance the Accra-Kumasi Expressway has been secured from domestic sources, with no borrowing involved.
President John Dramani Mahama has confirmed that $2 billion, sourced from taxpayers’ money, has been deposited in a special account at the Bank of Ghana.
“And let me also announce that this is our own money. We have not gone to borrow money from anywhere. This money is the taxpayers’ money,” the President stated at the handover ceremony of the cleared right-of-way on September 14, 2026.
No Borrowing, No Debt Burden
Finance Minister Dr. Cassiel Ato Forson has reinforced this commitment, assuring the nation that “we will not borrow a pesewa for this construction”.
He stated that the full amount required will be ready by December 31, 2026, and reiterated that the government plans to mobilise the required funds entirely from domestic sources, allowing the project to proceed without adding to Ghana’s debt burden.
Timely Payments to Contractors
The funds are lodged in a dedicated account to facilitate timely payments to the contractor throughout the duration of the project.
President Mahama assured that all payment certificates submitted by the contractor would be honoured promptly to prevent delays and ensure the project progresses as scheduled. The project is being managed by a special purpose vehicle, Accra Kumasi Expressway Limited, registered for this purpose.
The GAF Factor in Cost Savings
The government’s domestic financing strategy has been bolstered by significant cost savings from the involvement of the Ghana Armed Forces (GAF) Engineers.
The GAF cleared 175.6 kilometres of the right-of-way in just 19 weeks—beating a 20-week target—at an estimated cost of GH₵10.9 billion, compared with commercial contractor baselines of GH₵15–18 billion. This yielded billions of cedis in net savings.
The $2 billion domestic financing model represents a significant shift in Ghana’s infrastructure funding approach. If successfully executed, it could provide a template for future mega-projects, demonstrating that national development need not come at the cost of mounting external debt.
Business
From Raw Minerals to Luxury Brand: Ghana’s Gold Value-Addition Strategy Gains Global Momentum with UK Showroom

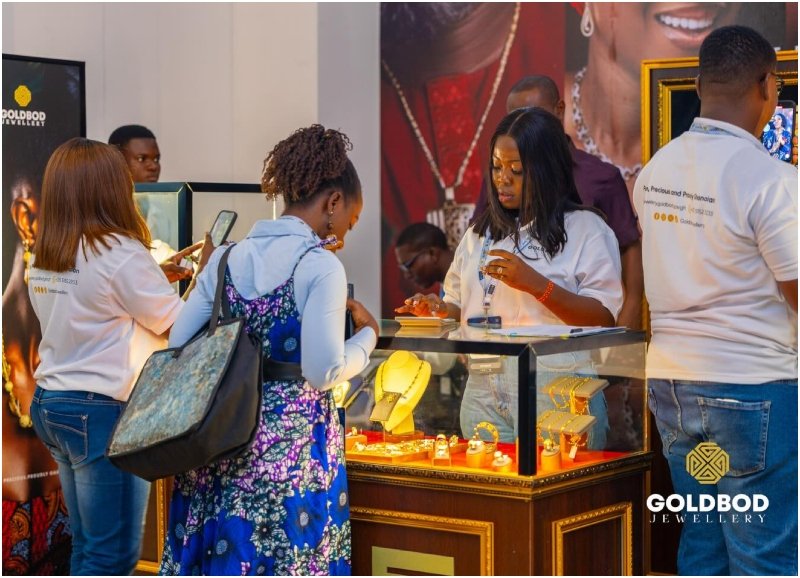
Ghana’s ambition to transform its gold sector from a raw mineral exporter into a competitive player in the global luxury jewelry market has received a significant boost, with indigenous company GOLDBOD Jewellery setting its sights on establishing a flagship showroom in the United Kingdom.
The move, which aligns with the government’s broader strategy of increasing value addition within the gold sector, reflects Ghana’s determination to maximize returns from its mineral resources through local beneficiation, manufacturing and branding initiatives designed to generate employment and enhance export earnings.
Chief Executive Officer of GOLDBOD Jewellery, Gertrude Emefa Donkor, recently paid a courtesy call on Ghana’s High Commissioner to the United Kingdom, Sabah Zita Benson, to present the company’s vision of showcasing premium jewelry and investment-grade gold products crafted from responsibly sourced Ghanaian gold.
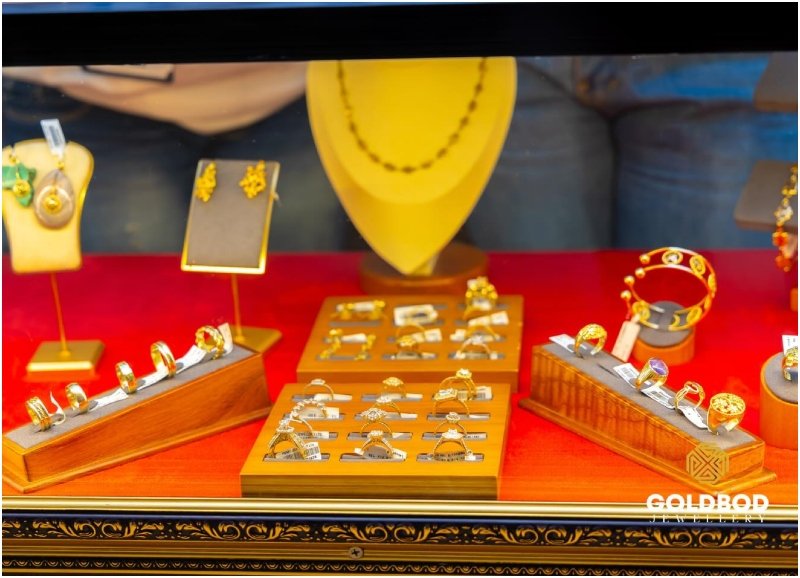
During the discussions, Miss Donkor highlighted the growing demand for the company’s innovative Gold Tablet, revealing that the product sold out during this year’s Ghana Party in the Park in London, one of the largest annual gatherings of the Ghanaian diaspora in Europe. She noted that the overwhelming patronage reflects growing confidence among diaspora communities and international consumers in authenticated Ghanaian gold products.
The planned expansion comes as Ghana, Africa’s leading gold producer, intensifies efforts to move beyond the export of raw minerals and establish a reputation as a trusted source of responsibly produced, value-added gold products.
The strategy is central to the country’s industrialization agenda, which seeks to create jobs, boost foreign exchange earnings and reduce dependence on primary commodity exports.
High Commissioner Benson reaffirmed the Mission’s commitment to supporting Made-in-Ghana products in the UK market, noting that the High Commission continues to collaborate with relevant public institutions, private sector stakeholders and business associations to create opportunities for Ghanaian enterprises seeking to expand internationally.
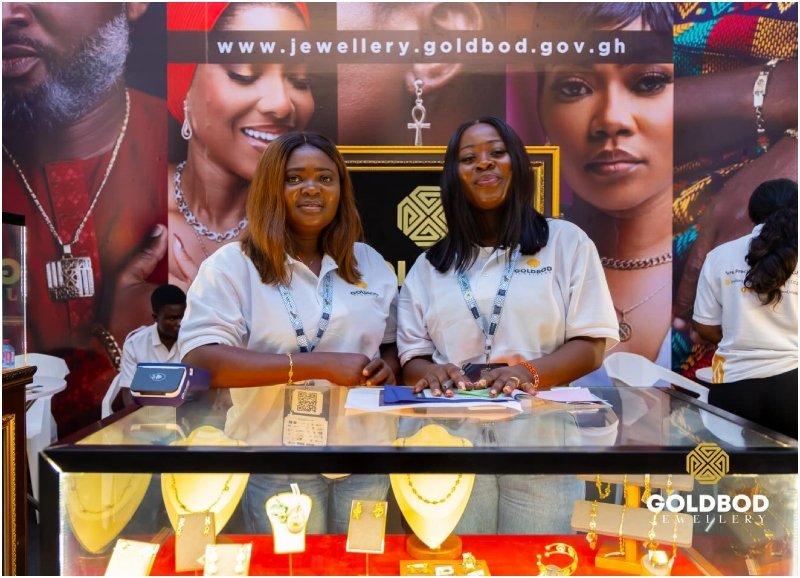
She expressed optimism that the proposed showroom would not only showcase the quality and craftsmanship of Ghanaian jewelry but also reinforce Ghana’s reputation as a trusted source of responsibly produced gold products. She added that initiatives of this nature complement the government’s broader agenda of leveraging trade, investment and economic diplomacy to promote sustainable national development.
The engagement underscores the evolving role of Ghana’s diplomatic missions in advancing economic diplomacy by facilitating market access for Ghanaian businesses and strengthening commercial partnerships abroad. The United Kingdom remains one of Ghana’s key trading partners and a strategic destination for Ghanaian exports, investment and diaspora engagement.
As Africa’s leading gold producer, Ghana has long been a major supplier of raw gold to international markets. However, successive governments have recognised that real economic transformation lies in retaining more value from the mineral through local processing, manufacturing and branding. GOLDBOD Jewellery’s UK expansion represents a tangible example of this vision taking shape on the global stage.
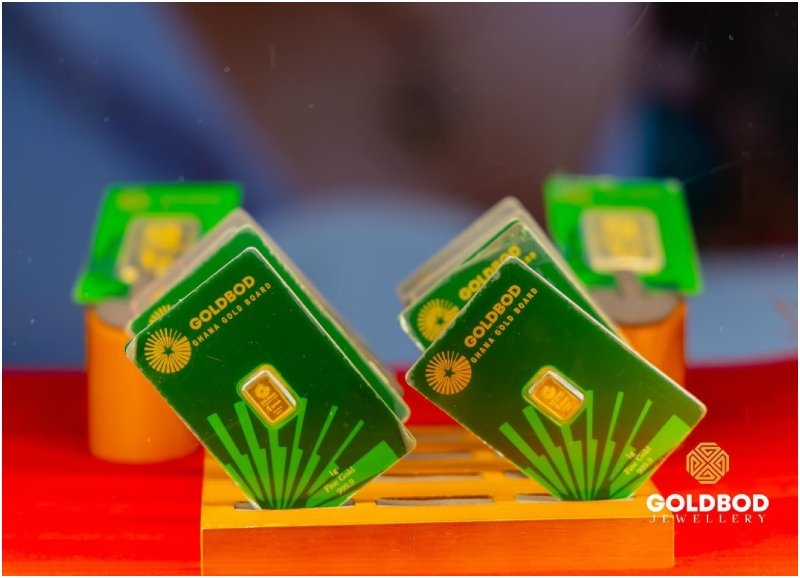
Industry observers note that the success of such initiatives could encourage more Ghanaian companies to explore international markets, particularly in sectors where the country holds a comparative advantage. The diaspora market, in particular, presents a significant opportunity for Ghanaian brands seeking to build consumer confidence and establish a foothold in competitive markets.
The meeting between Miss Donkor and High Commissioner Benson reflects growing collaboration between Ghana’s diplomatic missions and indigenous businesses as the country seeks to strengthen its presence in international markets while advancing industrialization, export diversification and value addition within the mining sector.
With the proposed showroom in the United Kingdom, GOLDBOD Jewellery is positioning itself as a flagship brand for Ghanaian gold, demonstrating that African products can compete at the highest levels of the global luxury market.
The move signals a new chapter in Ghana’s economic story, one in which the nation’s natural resources are transformed into globally recognised brands that tell the story of Ghanaian craftsmanship, quality and innovation.
Business
Ghana Beats the Odds: IMF Approves Final Review, Offering Blueprint for Africa’s Debt-Ridden Economies
Three years after defaulting on its debt, Ghana formally exits the IMF bailout program with a $318 million final disbursement—and a new reform framework that could show other distressed African nations the way forward
The Executive Board of the International Monetary Fund on Monday approved Ghana’s sixth and final review under the Extended Credit Facility (ECF) program, formally concluding the country’s three-year, $3 billion bailout arrangement and unlocking a final disbursement of approximately $318 million.
The Board also approved Ghana’s request for a 36-month Policy Coordination Instrument (PCI), a non-financing arrangement that will guide the country’s economic reforms now that the bailout has ended.
The approval marks the culmination of one of the most dramatic economic turnarounds in recent African history—a recovery that began in the depths of crisis in late 2022, when Ghana defaulted on most of its external debt, inflation topped 54%, and the cedi was in free fall.
“Ghana’s ECF-supported economic program has delivered substantial stabilization gains,” the IMF said in a May statement after reaching a staff-level agreement with the government. “Inflation has declined rapidly, international reserves have been rebuilt, and confidence in the cedi has improved.”
From Default to Credibility
Ghana entered the 36-month ECF arrangement in May 2023 with access to about $3 billion to help restore macroeconomic stability, implement fiscal reforms, and support the country’s debt restructuring program. At the time, the country was in the throes of its worst economic crisis in a generation.
The turnaround has been striking. Inflation has plunged from 54% in December 2022 to just 5.3% in June 2026. Gross international reserves have reached an all-time high of approximately $14.5 billion as of February 2026, providing nearly six months of import cover. The public debt-to-GDP ratio has fallen sharply from a peak of over 80% to 45% by June 2026.
Perhaps most significantly, Ghana’s sovereign credit ratings have improved from restricted default—”junk status”—to ‘B’ with a positive outlook, representing five distinct rating level upgrades.
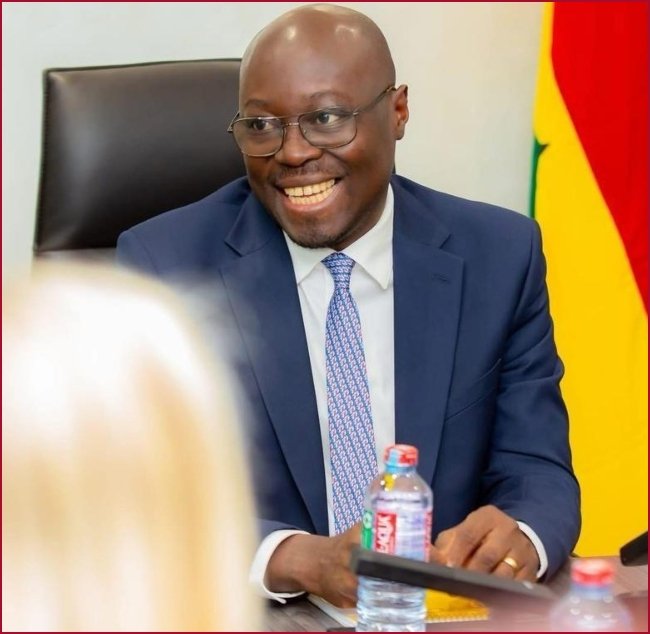
“Every quantitative performance criterion, but one, set for the final review has been met,” Finance Minister Dr. Cassiel Ato Forson told Parliament while presenting the 2026 Mid-Year Budget Review. He noted that Ghana achieved 10 out of 11 quantitative targets and 8 out of 10 structural benchmarks.
A Blueprint for Africa
For other African nations struggling with debt distress—including Zambia, Ethiopia, and Kenya—Ghana’s trajectory offers a potential roadmap. The country’s success demonstrates that aggressive fiscal consolidation, coupled with credible IMF engagement and good-faith debt restructuring, can restore market confidence within a relatively short timeframe.
The PCI framework that Ghana is now entering is particularly instructive. Unlike the ECF, the PCI does not provide direct funding. Instead, it offers closer policy engagement with the IMF and signals a country’s commitment to reforms, helping to strengthen investor confidence and attract support from development partners.
“Completing the ECF does not mean Ghana walks away from the IMF,” Forson explained. “It means Ghana changes the nature of the relationship.”
The new program will focus on six priority areas: growth-friendly fiscal consolidation, debt sustainability, fiscal transparency and governance, stronger monetary and exchange rate policy frameworks, financial sector stability, and economic diversification.
Forson described the PCI as “a structured, internationally monitored platform through which Ghana commits to a specific set of macroeconomic and structural reform policies, submits to regular independent review, and signals to the world that the discipline of the past eighteen months is not a temporary posture adopted under crisis conditions. It is a permanent feature of how this country will be governed.”
The Work Isn’t Over
Despite the celebration, the IMF has made clear that Ghana’s reform agenda is far from complete. The Fund has urged the government to press ahead with reforms in the energy sector, particularly efforts to improve efficiency at the Electricity Company of Ghana (ECG) through private sector participation.
“Priority should be given to tackling distribution and collection losses at ECG, including advancing private sector participation in the distribution segment,” the IMF stated.
The government has indicated that private sector participation in ECG is expected to commence by early 2027.
The PCI is also designed to help Ghana maintain macroeconomic stability, build resilience against external shocks, address structural imbalances, and support sustainable economic growth. With the global environment remaining uncertain—including potential spillovers from conflicts and volatile commodity prices—sustaining the reform momentum will be critical.
A New Chapter
Monday’s approval formally concludes Ghana’s 16th IMF program since independence. For a country that was written off by many international investors just three years ago, the milestone represents a remarkable redemption story.
“This milestone reflects improved fiscal performance, normalized relations with global creditors, and renewed market confidence,” said Felix Kwakye Ofosu, Minister of State for Government Communications.
Finance Minister Forson has already declared that Ghana does not expect to seek another IMF bailout in the foreseeable future. The country now aims to achieve “Investment Grade” status, a goal that would further lower borrowing costs and unlock long-term institutional investment for critical infrastructure.
For now, however, the immediate priority is clear: cement the gains, stay the course, and prove that Ghana’s recovery is not just a temporary reprieve—but a permanent transformation.

Making Every Square Metre Count: Interior Design Tips for Ghanaian Homeowners

Poor Posture Is More Than a Bad Habit: How Four Minutes a Day Can Help

Accra’s Pool Party Brings Music, Style and Detty December Energy
-
 Commentary2 days ago
Educated, Wealthy and Still Trapped: Why Women’s Advancement Falls Short of Empowerment
-
 Ghana News2 days ago
FBI’s Kash Patel Says Ghana Scam Network Targeted 89 U.S. Victims, Stole Nearly $10 Million
-
 Perspectives1 day ago
Russia-Africa Summit: The Search for Resources, Influence and War Resilience
-
 Ghana News2 days ago
Dr Issaka Yakubu Akparibo: Ghanaian Doctor Becomes First African Inducted into Global Aviation and Space Medicine Academy
-
 Health & Wellness2 days ago
When Weight Loss Stalls, Look Beyond the Scale
-
 Ghana News12 hours ago
Ghana’s Cyber Security Authority Challenges FBI’s Kash Patel’s Account Of Major Scam Operation in Accra
-
 Ghana News12 hours ago
How to Pay Chinese Suppliers Directly From Your Ghanaian Cedi Account
-
 Reels & Social Media Highlights1 day ago
Nana Akua Addo, Dumelo, and KFC: What Ghana Was Actually Talking About on Social Media