Perspectives
Bank of Ghana Balances on a Knife Edge

In this detailed analysis, Bright Simons dissects the Bank of Ghana’s audited 2025 financial statements, revealing that the central bank recorded a net loss of GH¢1.25 billion and a total comprehensive loss of GH¢2.80 billion. These losses have pushed its negative equity to approximately GH¢9 billion. Simons explains that the Bank is caught in a costly cycle, often described as a “sterilization treadmill,” where it mops up excess liquidity by borrowing back printed cedis at high interest rates. This process cost the Bank GH¢1.34 billion in 2025 alone, a figure that exceeds its total operating income.
Bank of Ghana Balances on a Knife Edge
By Bright Simons
Preliminaries
On 30th April, 2026, the Bank of Ghana (BoG) published its audited financial statements for 2025. By law, these should have been approved by the Board and submitted to the Finance Minister by end-March. They were not.
The Bank obtained a one-month extension, partly on the grounds that it had changed auditors – from Deloitte to KPMG – who needed time to come to terms with the books. And partly because additional scrutiny was requested around the gold operations and the Bank’s exposure to the Ghana Gold Board (GoldBod).
The statements were approved on 29 April and published on 1 May, barely meeting the secondary legal deadline for publication.
The numbers dropped like a bombshell into Ghana’s polarised political environment. As it became clear that the BoG recorded a net loss of $1.25 billion for the year, the Opposition NPP began to bay for blood. [The dollar amounts used throughout the text are sensitive to specific exchange rate assumptions, and may differ slightly from those in my earlier social media posts.]
Further reading showed that an additional $1.55 billion in other comprehensive income charges – driven by the accounting impact of a stronger cedi reducing the domestic-currency value of dollar assets of the BoG mostly held abroad – pushed total comprehensive losses to $2.80 billion. Cumulative negative equity (the “hole” in the BoG’s capital base) reached ~$9 billion at the end-2025 closing rate, widening from $3.99 billion a year earlier. As a share of GDP, the negative equity is approximately 8 per cent (depending on how exactly one estimates the relevant GDP metric). It is among the largest such positions reported by any central bank globally, and sustained across successive years. Big deal.
Three forces got us here, each one with its own fascinating story to tell.
Getting down to basics
Before examining the numbers, it helps to understand the basic mechanics of what the central bank does that generates these losses. It is not all that complicated, but it can get confusing pretty quickly.
Step 1: Creating Money to Buy Gold
Ghana produces gold, lots of it. It is Africa’s largest producer in fact. The Bank of Ghana wants this gold because it can be sold for dollars, and dollars are extremely precious in Ghana because they often dry up and drag the Cedi down. So, the Bank pays Cedis to the miners and takes their gold. But it is not like it has an infinite stash of cedis sitting in a vault. It usually “creates” what it needs, almost from thin air. When the Bank credits a GoldBod aggregator’s account for onward payment to miners, those cedis come into existence at that moment.
In 2025, the Bank purchased, in one set of transactions, approximately 2.9 million fine ounces of doré gold, worth roughly $7.6 billion at average market prices. Much of the funds used to pay for that gold was created in the way described above.
Step 2: Turning Gold into Dollars
The doré gold is shipped to LBMA-certified refineries, processed into investment-grade “bullion”, and either held as a reserve asset or sold on international markets. In 2025, the Bank sold 869,915 ounces of refined bullion for approximately $3.6 billion, and also sold roughly 2.9 million ounces of doré under the Gold for Reserves programme. The dollars flow into Ghana’s foreign reserves. Result: reserves rose from around $6.5 billion in early 2024 to $13.8 billion by end-2025, a high point in Ghana’s monetary history.
Step 3: Mopping Up the Cedis
But there is a catch, that I have spent months talking about. The cedis created in Step 1 are now circulating in the economy. If left there, banks will lend them, businesses and households will spend them, demand will outstrip supply, and prices of goods will rise. Inflation. The Bank’s primary mandate is to prevent exactly that. So, it needs to pull as much of those cedis back out as possible.
It does this by issuing short-term bills to commercial banks (in simple terms, it borrows from the bank and park the money). A bank hands the Bank of Ghana $8 million worth of cedis; the BoG gives the bank a piece of paper – IOU – promising to pay it back with interest in 14, 28, or 56 days. The cash is locked up. This process is called sterilisation, and the IOUs are called open market operation (OMO) bills.
By end-2025, the Bank had ~$9 billion of these bills outstanding at the closing rate, nearly triple the $2.22 billion outstanding a year earlier.
Step 4: Paying Interest on Its Own Borrowing
Those OMO bills carry interest at or near the monetary policy rate, which ranged from 27 per cent to 21.5 per cent through most of 2025. The Bank paid $1.34 billion in interest to commercial banks for the privilege of borrowing back the cedis it had itself created. That rate has come down significantly but there is no guarantee that it will stay down in the medium-term.
Step 5: The Loss Compounds
The Bank’s income from all sources – interest on its securities portfolio, fees, and foreign exchange trading, for instance – totalled roughly $1.01 billion in 2025 (excluding the one-off sale of a large part of Ghana’s gold reserves). Its sterilisation costs alone were $1.34 billion. Add operating expenses of $507 million, gold programme losses of $724 million, and other charges, and total operating expenses reached $3.03 billion against total operating income of $1.78 billion. The gap, the annual loss, was $1.25 billion.
That loss worsens an equity position that was already deeply negative. Every year that the cycle repeats the hole will grows deeper.
| In Plain Language The Bank of Ghana is running a three-step operation: (1) print cedis to buy gold, (2) sell the gold for dollars to build reserves, (3) borrow the printed cedis back at high interest to prevent inflation. The operation achieves its strategic goal – record reserves (which contributes to a strong Cedi) + lower inflation – but at a financial cost that exceeds the Bank’s income. |
Policy Solvency: Is the Bank Earning Enough to Do Its Job?
The Bank of Ghana is keen on “policy solvency”: the measure of whether its operating income covers the cost of its main objectives. Remember that the BoG is not like commercial banks. It doesn’t intend to make profits for its shareholders. It only needs to have the resources to implement monetary policy like preventing inflation and Cedi depreciation from getting out of hand.
For 2025, the BoG reported a policy solvency surplus of $440 million. We break down the details below.
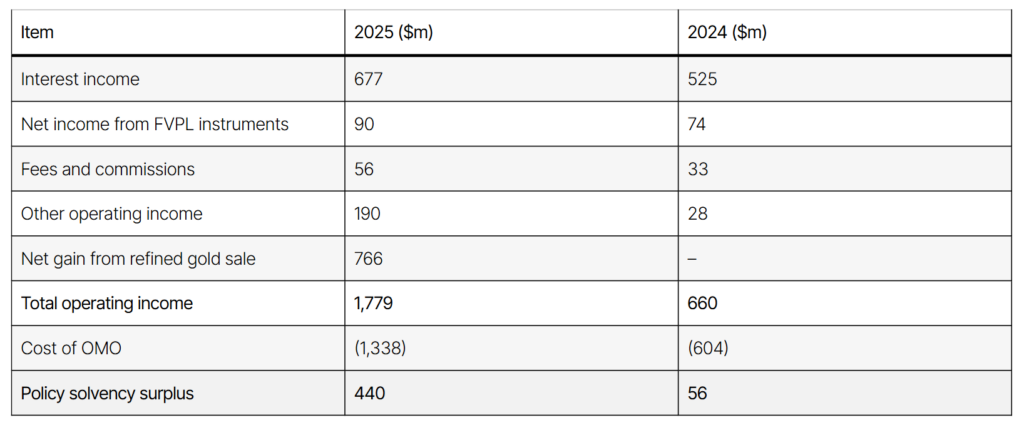
Look carefully and you would see that not much changed in its core operations to account for the large jump in income.
Strip out the $766 million one-off gain from selling half the country’s gold reserves, and the Bank posted a policy solvency DEFICIT of roughly $326 million.
The Core recurring income – such as interest, fees, and trading gains – fell materially short of the cost of squeezing cedis out of the system to keep the exchange rate stable, and by implication inflation in check. Policy solvency was achieved only because the Bank liquidated approximately half its gold holdings in a non-repeatable transaction.
Questionable Items Within “Other Operating Income”
The “other operating income” line, which is the only other item that differs materially from 2024, raises all manner of issues. It jumped from ~$28 million in 2024 to ~$190 million in 2025 – a roughly sixfold increase. The financial statements reveal that ~$172 million of this amount was a reimbursement from the Ministry of Finance for “fees and charges incurred in connection with Ghana’s Special Drawing Rights allocation from the IMF.”
It is all sorts of eyebrow raising. The Bank’s own accounts show that its total interest cost on IMF and SDR allocations was $35.6 million in 2025 (Note 11 of the financial statements: 444.8 million GHS). If the actual SDR-related expense was $35.6 million, on what basis did the Ministry reimburse $172 million – nearly five times the stated cost?
The IMF SDR allocations were given to countries as COVID-19 was raging. Normally functioning economies normally don’t touch their SDRs. But Ghana was anything but normal in the 2021 – 2023 timeframe. The records show that Ghana blew through its SDRs and hasn’t bothered to rebuild the holdings, thereby incurring interest expense of $172 million in 2025 on a ~$1 billion IMF SDR allocation. That’s over 17% of the amount.
That figure makes no sense because IMF interest rates for SDR allocations range from zero (if a country doesn’t spend the allocation) to between 3% to 4% in relevant periods. The amount indicated in the financial statements as a refund from the central government to the BoG for handling the interest payments on behalf of Ghana simply doesn’t add up. It is way more than justified by that declared objective alone.
The BoG’s financial statements describe this as reimbursement under “an established cost-sharing arrangement,” but provide no further detail on the calculation methodology or on what cumulative costs are being recovered. If this payment includes arrears from prior years, that context is absent from the notes. BoG seemed to be using accounting gymnastics to raise its income to understate its policy solvency deficit (i.e. that it is not making enough money to cover its core functions.)
Unsettled Gold Receivables
BoG’s “other assets” also jumped from $771 million in 2024 to $2.51 billion at closing rates in 2025. The financial statements do not provide a line-by-line breakdown adequate to explain this surge, but contemporaneous reporting indicates that a substantial portion reflects unsettled dollar proceeds from the Gold for Reserves programme. In that scheme, commercial banks that received gold or gold-linked foreign exchange allocations and had not completed settlement by year-end would have created receivables for the BoG.
However, if approximately $1.2 billion in receivables remain outstanding from programme counterparties, then this raises questions about both counterparty risk within the Domestic Gold Purchasing Program (DGPP) channel and whether the Bank’s reported reserve position includes claims that are not yet liquid.
“Losses” definitely matter
Because the Bank of Ghana creates the currency (Ghana Cedi) in which its obligations are denominated, it does not suffer from losses like a normal commercial bank.
A central bank can and some do operate as a going concern with negative equity. The Czech National Bank ran negative equity for 17 consecutive years after its exchange rate intervention programme generated large foreign-exchange losses. Chile, Israel, Mexico, and Slovakia have all experienced periods of negative capital while conducting effective monetary policy. The Reserve Bank of Australia reported negative equity of A$12.4 billion in 2023 from Quantitative Easing – related bond losses without any disruption to its operations.
But – and this is a very critical qualifier – the fact that a central bank can survive negative equity does not mean it can do so cost-free, or indefinitely, or in any institutional context.
Five ways the BoG’s negative equity situation can affect Ghana badly
1. “Sterilisation” can become a treadmill. Each year of losses means the Bank spent more cedis than it collected. Those extra cedis entered the economy. To prevent inflation, the Bank must sterilise them. It must issue more OMO bills, at more interest cost, generating more losses, and requiring more sterilisation. An effective compounding cycle. At GH¢93.6 billion (~$8.5 billion) in outstanding OMO liabilities and a policy rate in the region of 15 per cent, the annual interest bill alone hovers around $1.12 billion. If the gold programme continues injecting liquidity and the OMO stock keeps growing, the interest bill grows with it – even if the rate falls – because the base is expanding faster than the rate is contracting.
2. Passive money creation. A central bank that spends more than it earns is creating money as a byproduct of its own cost structure. Each dollar of operating loss is a dollar of new cedis that entered the economy without a corresponding withdrawal. In 2025, the Bank’s loss of $1.25 billion represented incremental money creation equivalent to roughly 1 per cent of GDP. We are talking about a structural inflationary impulse that the Bank must then sterilise at further cost. If care is not taken, a dangerous spiral can develop.
3. Negative carry on the portfolio. The Bank borrows short at Ghanaian rates (15 – 27 per cent) and earns returns on its assets at a blend of restructured domestic coupons (suppressed by the DDEP) and international rates (4 – 5 per cent). The result is a mismatch embedded deep in the structure of the Ghanaian economy. As long as Ghana’s risk premium keeps domestic rates well above global rates, the Bank’s portfolio will bleed. No efficiency measure or cost-cutting programme can fix a problem structurally rooted in the country’s term structure.
4. Seigniorage is shrinking. The theoretical defence of central bank losses rests heavily on “seigniorage” (the profit from issuing non-interest-bearing banknotes). As Ghana’s economy becomes more digital (for example: mobile money transactions begin to dwarf physical cash), the share of transactions settled in banknotes will decline. Each transaction that shifts from cash to mobile money reduces the Bank’s seigniorage base, and quietly erodes the income stream that supposedly makes losses irrelevant.
5. The consolidated fiscal position weakens. The central bank and the government are both part of the public sector. The Bank’s annual losses are “quasi-fiscal” deficits. Which is a fancy way of saying that public expenditure that does not appear in the government budget is nonetheless a liability of the government because the central government remains the backstop.
The IMF program targets a government primary surplus of 1.5 per cent of GDP. But if the Bank is simultaneously running quasi-fiscal losses of 1 per cent of GDP, the consolidated public sector position is weaker than the headline fiscal numbers suggest. These shadows can’t be ignored forever.
Recapitalisation: Can the Government Fill a $9 Billion Hole?
The BoG and the Ministry of Finance signed a Memorandum of Understanding (MOU) on 6 January 2025 committing the government to a phased recapitalisation of the BoG over 2026 – 2032. The Bank of Ghana Act was amended (Act 1158) to raise minimum authorised capital from $1 million to $100 million (using USD 1 equals GHS 10 here) and to create a formal framework requiring the government to inject capital within 90 days of the BoG’s Board request.
In the current circumstances, the math looks brutal. Restoring equity from negative ~$9 billion billion to the new statutory minimum of positive $96 million requires approximately $9.1 billion. Spread over six years, that is roughly $1.5 billion annually. An amount equivalent to roughly 8 per cent of the government’s total annual revenue, or about 1.2 per cent of GDP per year.
Is this realistic? Consider the competing demands on the same fiscal envelope:
Fiscal consolidation. The IMF programme requires a primary surplus of 1.5 per cent of GDP. In 2024, the government missed this target by 3.8 percentage points, largely because ministries accumulated GH¢68.8 billion ($4.8 billion) in commitments outside the GIFMIS system. We now know the link to predominantly election-related infrastructure spending. The 2024 audit disqualified 12.5 per cent of these payables for procedural irregularities. Any recapitalisation that adds to public debt works against the government’s embraced IMF’s debt reduction targets, and particularly the lowering of public debt to 47% of GDP by 2030.
Bank recapitalisation. The government is simultaneously recapitalising state-owned commercial banks through the Ghana Financial Stability Fund, which has already disbursed GH¢5.2 billion (~$365 million) in bonds.
Energy sector arrears. Legacy and accumulating debts to independent power producers and fuel suppliers run into billions of dollars over the medium-term. A new fuel levy was introduced in 2025, but its yield covers only a fraction of the annual shortfall.
Infrastructure and social spending. The new administration has committed to expanded social protection, teacher training, and health infrastructure. Plus the Big Push. Each of these is politically non-negotiable.
There are hints that the government intends to handle the recapitalisation by issuing non-tradeable bonds. Such bonds will merely address the equity optic without contributing to operational profitability. The BoG would still needs to earn enough from other sources to cover its sterilisation costs, and the government would still bear the fiscal cost of a larger debt stock.
Fundamental tension: every cedi of recapitalisation bonds adds to the very public debt that the IMF programme is designed to reduce, leading to a very tall order.
GANRAP: The Gold Programme’s Risks Going Forward
The Domestic Gold Purchase Programme (DGPP) has been rebranded as the Ghana Accelerated National Reserve Accumulation Programme (GANRAP). Until the BoG can crack an effective private sector solution, it will continue to purchase domestically produced gold using mostly newly created cedis, convert into monetary gold or sell for dollars, and sterilise the resulting liquidity.
Whilst the DGPP has driven reserves accumulation, the financial cost has been substantial and is structurally embedded in the programme design.
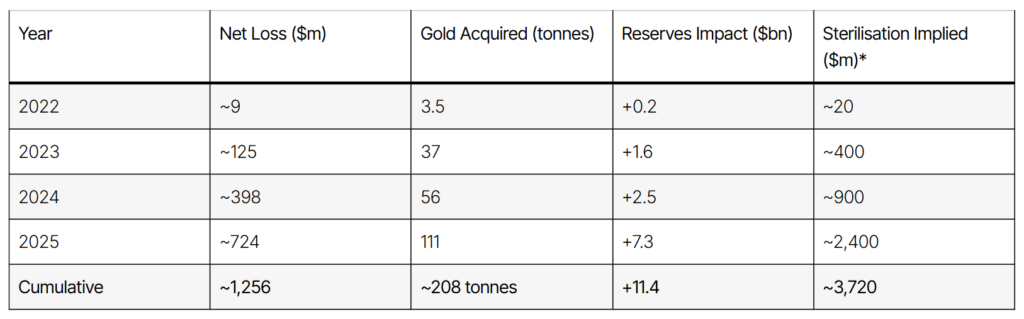
Four structural risks attend GANRAP’s continued operation:
Rate gap. The Bank buys doré at market prices but records it at official rates. The spread between the two – reflecting refining losses, assay fees, GoldBod agent commissions, and offtake discounts – constitutes a permanent operating drain. The Bank has indicated that unit costs are being reduced under GANRAP, but has not published the revised fee & cost schedule.
Sterilisation arithmetic. Each dollar of gold purchased domestically injects approximately GH¢12.50 into the economy (at 2025 average rates). Sterilising that amount at a 15 per cent rate costs the Bank GH¢1.88 per year – or $0.15 per dollar of reserves acquired. Over a two-year holding period before the gold is refined and banked, the sterilisation cost alone consumes 30 per cent of the dollar value of the reserve gain. Central banks that acquire reserves by purchasing dollars with existing cedi holdings, or by receiving IMF disbursements, incur a fraction of this cost.
GoldBod counterparty exposure. The Bank’s specific exposure to GoldBod, the intermediary for artisanal and small-scale gold purchases, is not separately disclosed in the financial statements. The IMF’s 5th ECF Review noted that losses from artisanal and small-scale gold transactions had reached $214 million. We now know that the overall exposure was more than 4x that amount. The Gold-for-Oil programme (which used gold sales to finance petroleum imports) was discontinued in March 2025 after cumulative losses, but the G4R programme continues under a new label with the same intermediation structure.
Diminishing marginal returns. Ghana’s reserves at $13.8 billion provide 5.7 months of import cover. Each additional dollar of reserves provides incrementally less insurance value. The jump from 1 month to 3 months of cover is transformative; from 5 to 6 months, the marginal benefit is modest while the sterilisation cost remains constant. Continuing to accumulate at 2025 pace imposes annual costs exceeding $1 billion for diminishing strategic gain. And now there is talk of jacking up coverage to 15 months based on large monthly purchases of gold. A situation that will jack up gold channel – sterilisation costs, lead to much higher opportunity cost of resources tied up in reserves earning minimal interest, and all for very modest insurance benefits.
Alternative Approaches with Lower Costs
The Bank of Ghana’s method of reserve accumulation – domestic gold purchase financed by money creation and sterilised at domestic interest rates – is among the most expensive possible approaches. Several alternatives would deliver similar or superior results at lower financial cost:
1. Mandate gold royalty payments in-kind rather than in cash. Large-scale mining companies currently pay royalties in cedis. If a more significant portion were payable in refined gold delivered directly to the Bank’s reserve account, the Bank would acquire gold without creating any domestic liquidity. No sterilisation cost because the gold arrives already refined. Drawback: requires legislative amendment and renegotiation of mining agreements. Companies would resist because it removes their flexibility to time royalty payments. Still an idea worth exploring further.
3. Channel gold purchases through a fiscal agent rather than the central bank. If the Ministry of Finance (or a sovereign wealth vehicle) purchased gold using existing budgetary resources and transferred it to the Bank, the liquidity injection would come from fiscal spending already accounted for in the budget – rather than from new money creation. The Bank would receive gold without printing cedis, eliminating the sterilisation cost entirely. Drawback: requires fiscal space that the government does not currently have, and creates a different form of fiscal-monetary entanglement.
4. Slow the pace of accumulation. With reserves at 5.7 months of import cover, Ghana has already exceeded the standard adequacy threshold. Reducing the pace of domestic gold purchases by 50 per cent would halve the sterilisation cost while maintaining reserves above comfortable levels. Drawback: politically difficult. The gold programme is popular, enriches domestic capitalists, and aligns with resource nationalism sentiments. GoldBod, mining communities, and aggregators are all powerful constituencies.
5. Restructure the entire gold channel creatively. We have recently described a “Trust-Chain” model that could shift GoldBod from state trader to regulator of a transparent, competitive gold network. Private or semi-private financiers fund aggregators, multiple buyers compete for gold, offtake is auctioned broadly, and risks like price, purity, FX, and logistics are explicitly allocated rather than dumped on BoG. In the proposed model, real-time traceability, published benchmarks, audits, and risk-sharing preserve reserve-building benefits while reducing subsidies, opacity, and public balance-sheet losses.
The political economy barriers to all these alternatives are formidable. The DGPP/GANRAP has created a domestic ecosystem of aggregators, agents, transporters, and small-scale miners who depend on continued central bank purchases. GoldBod itself is a relatively new institution with institutional momentum. Slowing or restructuring the programme would generate concentrated losses among these groups while distributing diffuse gains (lower inflation risk, and reduced central bank losses) across the general population.
If you know your katanomics theory well you also know that this is exactly the political dynamic that makes reform difficult in any democracy. Simply because there simply isn’t a critical policy audience to constitute a counterweight to the political jobbers and vested interests.
So long as the Cedi remains stable and inflation stays down, apathy about the situation shall dominate.
Should citizens care?
To wrap up, these are the key issues to keep track of.
Inflation risk. The sterilisation treadmill creates a latent inflation reservoir. The GH¢93.6 billion in OMO bills will eventually mature. If the Bank cannot roll them over – because banks demand higher yields, or because the stock has grown too large relative to the banking system’s appetite – the cedis flood back into the economy. In 2025, the OMO stock was equivalent to roughly 34 per cent of broad money (M2+). An uncontrolled unwinding of even a quarter of this stock would release enough liquidity to reignite inflation sharply.
Higher borrowing costs. Commercial banks earning 15 – 25 per cent risk-free on OMO bills (as the policy rate rebounds) have little incentive to lend to businesses or households at comparable rates. Why take credit risk on a small enterprise when the central bank offers guaranteed returns? The OMO book crowds out private credit. If the OMO stock remains bloated, lending rates to businesses and households will remain elevated.
Forgone government spending. Every cedi the government eventually transfers to recapitalise the Bank is a cedi not spent on schools, hospitals, roads, or social protection. If the recapitalisation MOU is honoured, $1.3 billion per year – roughly equivalent to Ghana’s entire 2024 capital expenditure on health – will flow from the Treasury to the Bank’s balance sheet for seven years. If the MOU is not honoured, the Bank’s negative equity persists, and the risks described above intensify.
Currency vulnerability. The cedi appreciated 41 per cent against the dollar in 2025 – a remarkable performance driven by strong reserves, high real interest rates, and improved investor confidence. But this appreciation was partly sustained by the very OMO operations that are financially unsustainable for the Bank. If the Bank is forced to reduce sterilisation (because the cost is too high), excess cedis will chase dollars, reversing the appreciation. A 20 per cent depreciation from current levels would erase the purchasing power gains that Ghanaian households experienced in 2025 and push imported food and fuel prices higher.
Conclusion: yes, citizens should care
The Bank of Ghana’s negative equity, taken in isolation, is not the catastrophe that partisan commentary suggests. Central banks are not commercial banks. They do not face insolvency in the conventional sense. Their mandate is price stability and financial system soundness, and the Bank has delivered measurably on both in 2025: inflation fell to 5.4 per cent (within the target band for the first time since 2021), reserves reached historic highs, the banking sector returned to profitability, and the cedi’s appreciation was the strongest among emerging market currencies.
What should worry us is the sustainability of the operating model that produced these results. The Bank ran a $1.25 billion loss to achieve them. It achieved policy solvency only by liquidating half its gold reserves – a one-time manoeuvre. Core operating income fell $326 million short of sterilisation costs. The OMO liability stock tripled in a year. The recapitalisation plan depends on a government that has never sustained seven consecutive years of fiscal discipline. And several items in the financial statements – the SDR reimbursement, the unsettled G4R receivables, and the opacity of GoldBod exposures – suggest that the reported numbers may present a more favourable picture than the underlying reality warrants.
The gold programme has been clearly impactful regarding reserves. But as we have seen, it can be greatly improved.
Ghana’s economy has absorbed extraordinary shocks since 2022 – sovereign default, debt restructuring, currency collapse, inflation above 50 per cent etc. The Bank of Ghana deserves some credit for the signs of recovery. But the institution’s balance sheet is carrying the accumulated cost of stabilisation in a way that constrains its future flexibility.
If the next shock arrives before the balance sheet is repaired, the Bank will face it with less ammunition, less credibility, and less room to manoeuvre than it had in 2022.
No one can say that this is not something citizens should worry about.
Credit: brightsimons,com
The author, Bright Simons, is a Ghanaian technologist, social innovator, entrepreneur, writer, social and political commentator. He is the vice-president, in charge of research at IMANI Centre for Policy and Education. He is also the founder and president of mPedigree.






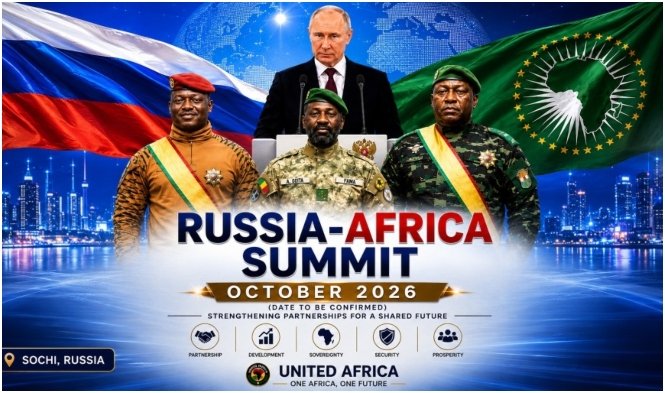
As Moscow prepares to host the third Russia-Africa Summit on 28–29 October 2026, the gathering arrives at a moment of heightened scrutiny. Nearly five years into its war in Ukraine, Russia is seeking to prove that its partnerships with African states have survived Western sanctions and remain strategically valuable. But the deeper question is what Africa gains in return. Drawing on trade figures, security partnerships in the Sahel, and the intersection of military cooperation with resource interests, this analysis by Joseph McCarthy examines whether the relationship is genuinely reciprocal or whether Africa is becoming an increasingly important source of the political influence, strategic resources, and economic resilience that Moscow needs to sustain its own geopolitical ambitions. Read the full article below.
Russia-Africa Summit: The Search for Resources, Influence and War Resilience
As the Ukraine war deepens Russia’s search for strategic resources, political allies and economic resilience, the third Russia-Africa Summit raises a difficult question: what does Africa gain in return?
Russia’s renewed engagement with Africa should be understood against the backdrop of a war in Ukraine that has become a test of Moscow’s economic, military and political endurance. Since the invasion of Ukraine, Russia has faced extensive Western sanctions, restrictions on trade and finance, and increasing pressure on the sources of revenue that sustain its war effort. In this environment, Africa has acquired a significance that extends beyond traditional diplomacy. The continent offers Moscow political partnerships, alternative markets, military cooperation and, critically, access to valuable natural resources and potential revenue streams that can help Russia withstand external pressure.
This helps explain the evolution of the Russia-Africa summits. The first summit, held in Sochi in 2019, was largely presented as an effort to rebuild and institutionalise Russia’s relationship with Africa, with trade, investment, security and political cooperation at the centre of the agenda. By the time of the second summit in St Petersburg in 2023, however, the geopolitical context had changed dramatically. Russia was already deep into its war in Ukraine and under extensive Western sanctions. The summit therefore served not only to deepen economic and political relations but also to demonstrate that Moscow remained capable of maintaining significant partnerships outside the Western bloc.
The third summit schedule on 28-29 October 2026, comes at an even more consequential moment. Russia is seeking to demonstrate that its relationship with Africa has survived the prolonged Ukraine war and remains capable of producing strategic benefits. The question for African governments should increasingly be whether the relationship is producing comparable benefits for them. Moscow’s partnership with Africa cannot be assessed only through diplomatic declarations, military agreements or high-level summits. It should also be judged by what African states receive in return and by what Russia gains from the relationship.
One of the most important areas to examine is natural resources. Russia’s interest in Africa is not simply about obtaining diplomatic support. Access to gold and other strategic commodities can provide alternative sources of revenue at a time when Moscow is seeking to reduce the impact of Western sanctions. Gold is particularly important because it can be traded through opaque networks and converted into revenue outside conventional financial channels. The U.S. Treasury has previously linked Wagner-associated gold operations in Africa to the financing of the group’s activities, including its operations in Ukraine. This does not mean that every Russian engagement with an African resource-producing state is designed to finance the Ukraine war.
It does, however, demonstrate why African resources can have strategic value for a Russia seeking to sustain its power and resilience under sanctions. The same logic extends beyond gold. Russia has increasingly shown interest in energy and critical raw materials, while its security partnerships in countries such as Mali and the Central African Republic have created relationships in which military and political cooperation can intersect with economic and resource interests. The emerging model therefore deserves closer scrutiny, Russia provides security assistance and political backing, while gaining influence, commercial opportunities and potentially privileged access to resources.
Mali provides one of the clearest case studies. Russia’s military presence in the country began with the arrival of Wagner personnel in 2021 and subsequently evolved into the Africa Corps structure. Moscow has presented this relationship as an alternative to Western security partnerships and as evidence of Russia’s willingness to assist African states in defending their sovereignty. Yet the relationship also raises a fundamental question: what does Russia receive in return for its military and political support?
That question becomes particularly important when the wider context of the Ukraine war is considered. If Russia can secure access to gold and other strategic resources, strengthen relationships with resource-rich governments and establish alternative economic channels, those relationships can help Moscow mitigate the effects of sanctions and sustain its broader strategic capacity. The relationship should therefore not be viewed solely through the narrow lens of counterterrorism. It is also part of a wider contest over resources, influence and economic resilience.
The economic figures contained in the summit case study reinforce the need to ask what kind of partnership Moscow is actually building. At the 2019 Sochi summit, Vladimir Putin announced a target of increasing Russia-Africa trade to $40 billion. According to Russian data cited in the document, trade stood at $27.7 billion in 2025, while Russia accounted for less than 1 percent of foreign direct investment in Africa. These figures do not prove that Russia’s Africa strategy has failed, nor do they capture every form of strategic value that Moscow derives from the continent. If Russia’s conventional economic footprint remains relatively modest, why is Moscow investing so heavily in strategic relationships with African states? One answer is that the value of Africa to Russia cannot be measured by trade and investment alone. Political influence, military access, diplomatic support, alternative markets and access to natural resources can all have strategic value. For a country fighting a prolonged war under sanctions, these forms of influence can become as important as conventional economic indicators.
This is why the third Russia-Africa Summit should be examined as more than another diplomatic gathering. Moscow wants to use the summit to demonstrate that its partnership with Africa remains strong despite the Ukraine war. The circumstances surrounding the meeting expose the tension at the heart of that claim. African officials are being asked to travel to Moscow while Ukrainian drone attacks have repeatedly disrupted air traffic around the Russian capital. On September 20 an attack involving more than 450 drones caused fresh disruption in the Moscow region, while Air Tanzania temporarily suspended its Moscow route following a risk assessment. The irony is difficult to ignore. Russia presents itself as a security partner for Africa, yet some African officials must consider their own security when travelling to the Russian capital. More importantly, African governments must now assess whether the strategic benefits of their relationship with Moscow justify the risks and costs associated with it.
For Ghana, this calculation is particularly important. The security consequences of Russia’s growing involvement in the Sahel cannot be separated from Ghana’s own national and regional security interests. A source close to the Ghanaian delegation cited in the summit document questions whether the relationship is genuinely “win-win” and points directly to the deteriorating security situation in the Sahel and its spillover towards Ghana’s northern borders. This should concern African governments is Russia’s engagement with Africa primarily delivering security and development benefits to African states, or is Africa increasingly becoming an important source of the political influence, strategic resources and economic resilience that Moscow needs to sustain its own geopolitical ambitions?
The answer is unlikely to be simple. Russia’s relationship with Africa serves multiple purposes, and resource access is only one component of a broader strategy. But the Ukraine war has changed the calculation. What may once have been presented principally as an effort to expand trade, investment and diplomatic relations now also has to be viewed through the lens of Russia’s need to preserve strategic autonomy, withstand sanctions and maintain the capacity to wage a prolonged war.
The third Russia-Africa Summit therefore represents a test not simply of whether African leaders will continue to engage Moscow, but of whether Russia can convince them that this engagement is genuinely reciprocal. For African states, the critical question is no longer whether Russia wants a deeper relationship with Africa. It clearly does. The more important question is what Moscow needs from Africa, what Africa receives in return, and whether the balance between the two is becoming increasingly unequal.
Joseph McCarthy is an analyst and researcher specialising in governance, security and political transitions in the Sahel. He writes on geopolitics, development and African diplomacy. joecarthy30@gmail.com
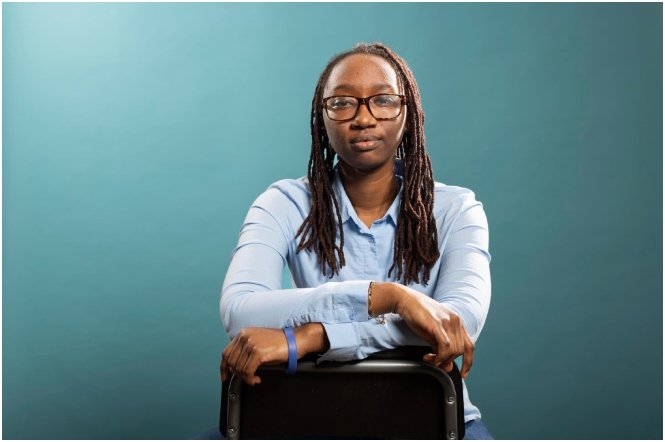
In Ghana, as in much of the world, a woman’s university degree, her salary, and her professional title are often taken as proof that she has made it; that she is empowered. But for many educated and wealthy women, those markers of advancement coexist with something far darker: violence, control, and a silence that their status only deepens. Drawing on Ghanaian data and international research, this analysis by Shallom Abla Lumor examines why resources alone do not guarantee agency, why economic abuse can erode independence, and why the women best positioned to leave are sometimes the ones least seen. It asks a harder question than whether women are advancing: whether they are actually free. Read the full article below.
Educated, Wealthy and Still Trapped: Why Women’s Advancement Falls Short of Empowerment
By Shallom Abla Lumor | Email: princesshallom@gmail.com
She has a university degree, perhaps two. She has a good job, earns her own money and pays a large share of the household bills. She may be a lecturer, a doctor, a banker or a lawyer. From the outside, we call her an empowered woman.
Yet she may be afraid to disagree with her husband. She may earn a good income and have little say over how it is spent. She may stay in a violent marriage because of her children, her church, her family name, fear for her safety, or what people will say.
Her degree and income tell us about her advancement. Whether she has power over her own life is a separate question.
Resources and the freedom to use them
Development scholar Naila Kabeer (1999) describes empowerment as the ability to make strategic life choices where that ability was previously denied. She separates resources, such as education and income, from agency, the ability to set goals and act on them. Resources make agency possible. They do not guarantee it.
So our questions must go further. Can she control the money she earns? Can she disagree with her partner without fear? Can she safely leave a dangerous relationship?
Education protects, up to a point
Ghana’s own data shows that education matters. Analysing the 2022 Ghana Demographic and Health Survey, Kwamena Sekyi Dickson, Castro Ayebeng and Joshua Okyere (2024) found that 36.4 percent of the married or cohabiting women in their sample had experienced some form of intimate partner violence. Women with secondary education or more had about 60 percent lower odds of having experienced it than women with no formal education.
That is a strong reason to keep investing in girls’ education. Lower odds still leave many educated women exposed. Even in the most educated group, about one in five women (19.2 percent) had experienced partner violence, compared with 41.7 percent of women with no formal education. The same study identified a partner’s dominance as an important predictor of violence, and a degree does little to change the man a woman comes home to.
Earning money and controlling it
Researchers including Judy Postmus and colleagues describe economic abuse as a distinct form of intimate partner abuse: controlling a woman’s access to money, monitoring her spending, running up debts in her name, or interfering with her work. A good salary offers limited protection when someone else decides how it is used.
Abuse can also wear away the independence a woman once had. Using police and employment records for the whole of Finland, economists Abi Adams-Prassl, Kristiina Huttunen, Emily Nix and Ning Zhang (2024) found that women whose partners were later reported for physical violence saw their earnings and employment fall sharply as soon as they moved in with these men, compared with similar women. The authors read this as economic suppression: abusive men weakening a woman’s ability to support herself and, later, to leave.
When her success collides with his beliefs
In a US study using a national sample of 4,296 people surveyed in the late 1980s, Maxine Atkinson, Theodore Greenstein and Molly Monahan Lang (2005) found that a wife’s share of household income was associated with a higher likelihood of abuse only among husbands with traditional gender beliefs. In Australia, Yinjunjie Zhang and Robert Breunig (2023) found that women who out earned their partners reported partner violence at a rate about 33 percent above the average, and emotional abuse about 20 percent above it. The authors concluded that the pattern points to norms about male breadwinning.
These studies show associations, from countries far from Ghana, so we should not borrow their numbers. Their question still applies here. If a man has been taught that a husband must always be the head and the main provider, what happens when his wife earns more? The risk lies in a belief system that reads her success as a threat to his authority.
Status can become its own prison
We assume a wealthy, educated woman would find it easier to speak up. The American psychotherapist Susan Weitzman suggests it can be harder. Drawing on interviews with fourteen affluent women, her book Not to People Like Us (2000) describes what she calls “upscale violence,” and argues that police, courts and counsellors often overlook such women because many people believe abuse happens only to other kinds of women.
When she does speak, she hears: “You are a lawyer, how can you allow this?” “You have your own money, why don’t you leave?” Such questions turn his behaviour into a verdict on her intelligence.
Children, church and the cost of leaving
In her master’s research at VID Specialized University (2020), Elorm Ama Stiles-Ocran interviewed ten Anlo Ewe survivors of domestic violence. They named poverty, the effects of divorce on their children, the shame and stigma of violence and divorce, fear of further violence, and church teaching on marriage as reasons they felt there was no way out. In a 2023 article in the African Journal of Gender and Religion, she draws on the stories of thirteen abused Christian women in a mainline church in southern Ghana to examine how theology shapes their agency.
Faith gives many women strength. In these women’s accounts, it could also hold them in place, when submission was taught as silence or when keeping the marriage together counted for more than the safety of the woman inside it.
Church leaders disagree about the church’s part in this. On 12 April 2022, the then Presiding Bishop of the Methodist Church Ghana, Most Rev Dr Paul Kwabena Boafo, said it was unwise to stay in an abusive marriage in the name of religion or society, and spoke about pastors who had persuaded abused members to stay. The next day, Rev Prof Johnson Kwabena Asamoah-Gyadu, now Presiding Bishop of the same church, said no Christian church encourages members to remain in abusive marriages and that the church was not to blame, while urging churches to protect victims and discipline abusers. Survivors deserve to know which of these they will meet in their own congregation.
Leaving also carries danger. A US study led by Jacquelyn Campbell (2003) compared 220 women killed by intimate partners with 343 women living with abuse, and found that separating from a controlling partner after living together was associated with a higher risk of being killed. Ghana’s context differs, yet a woman who has not left may understand the risk better than those judging her.
What we still don’t know
Ghana has the Domestic Violence Act, 2007 (Act 732) and the Domestic Violence and Victim Support Unit (DOVVSU) of the Ghana Police Service. Yet we have very little Ghanaian research on abuse among educated and wealthy women, and most of what we know about “upscale” abuse comes from abroad. The more firmly we picture the abused woman as poor and uneducated, the less likely we are to see her when she is a doctor or a director.
What each of us can do
Families can believe a daughter who reports abuse and stop sending her back to manage the marriage. Pastors can treat abuse as a safety matter first and refer survivors to DOVVSU and trained counsellors. Employers can offer confidential support, knowing senior staff may be living with violence at home. Men can challenge the idea that a wife’s income diminishes her husband. Friends can ask, “What do you need to be safe?”
A woman’s degree, income and title are achievements worth celebrating. Empowerment asks whether she can use them to shape her own life, freely and safely, and whether her home, church and community let her.
Sources
- Kabeer, N. (1999). Resources, agency, achievements: Reflections on the measurement of women’s empowerment. Development and Change, 30(3).
- Dickson, K. S., Ayebeng, C. and Okyere, J. (2024). Unveiling Shadows: Investigating women’s experience of intimate partner violence in Ghana through the lens of the 2022 Demographic and Health Survey. PLOS ONE. https://doi.org/10.1371/journal.pone.0309564
- Postmus, J. L., Plummer, S. B. and Stylianou, A. M. (2016). Measuring economic abuse in the lives of survivors. Violence Against Women, 22(6).
- Adams-Prassl, A., Huttunen, K., Nix, E. and Zhang, N. (2024). The dynamics of abusive relationships. Quarterly Journal of Economics, 139(4). https://doi.org/10.1093/qje/qjae022
- Atkinson, M. P., Greenstein, T. N. and Lang, M. M. (2005). For women, breadwinning can be dangerous: Gendered resource theory and wife abuse. Journal of Marriage and Family, 67(5).
- Zhang, Y. and Breunig, R. (2023). Female breadwinning and domestic abuse: Evidence from Australia. Journal of Population Economics, 36(4). https://link.springer.com/article/10.1007/s00148-023-00975-9
- Weitzman, S. (2000). Not to People Like Us: Hidden Abuse in Upscale Marriages. Basic Books.
- Stiles-Ocran, E. A. (2020). No way out? The dilemma of survivors of domestic violence and the church’s response in Ghana. MA dissertation, VID Specialized University. https://hdl.handle.net/11250/2825498
- Stiles-Ocran, E. A. (2023). Theology and women’s agency in the context of intimate partner violence in Ghana. African Journal of Gender and Religion, 29(1), 74 to 101. https://hdl.handle.net/11250/3082947
- Stiles-Ocran, E. A. [Title and year to confirm]. Religion and Development, 4(2 to 3), from p. 213. https://brill.com/view/journals/rnd/4/2-3/article-p213_5.xml
- Campbell, J. C. et al. (2003). Risk factors for femicide in abusive relationships: Results from a multisite case control study. American Journal of Public Health, 93(7). https://pubmed.ncbi.nlm.nih.gov/12835191/
- Ghana News Agency (12 April 2022). Don’t die in abusive marriage, Bishop Boafo. https://gna.org.gh/2022/04/dont-die-in-abusive-marriagebishop-boafo/
- Ghana News Agency (13 April 2022). No church supports abusive marriage, Clergyman. https://gna.org.gh/2022/04/no-church-supports-abusive-marriageclergyman/
Commentary
As Ghana Advances Move to Join the BRICS, These Are Among The Potential Benefits From the Deal
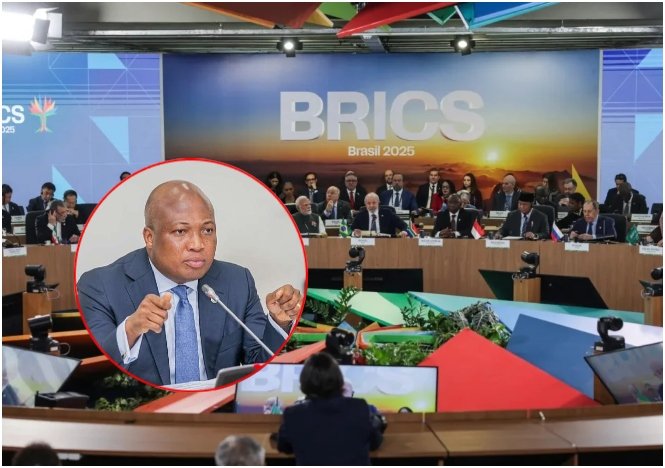
Ghana is preparing to formally apply to join BRICS, opening a new chapter in the country’s effort to diversify its international partnerships and gain greater room to manoeuvre in an increasingly fragmented global economy.
Foreign Affairs Minister Samuel Okudzeto Ablakwa announced on October 6 that President John Dramani Mahama’s Cabinet had approved Ghana’s decision to submit a formal application to the bloc.
“Another major highlight which I am disclosing to the Ghanaian people for the first time is that the Cabinet of President John Dramani Mahama has decided that Ghana should put in a formal application to join BRICS,” Ablakwa said, according to the Ghana News Agency.
The announcement places Ghana inside a much larger geopolitical conversation.
BRICS has evolved considerably from the original grouping of Brazil, Russia, India and China. South Africa joined in 2011, while Egypt, Ethiopia, Iran, Saudi Arabia and the United Arab Emirates were added in the latest major expansion. Indonesia subsequently became a full member.
The group also created a partner-country category, with Nigeria, Uganda and other countries joining that framework. Partner status gives countries opportunities to participate in selected BRICS meetings and discussions, although it does not provide the same participation as full membership.
Ghana is now seeking something more ambitious: membership.
But joining BRICS would not, by itself, transform Ghana’s economy.
The real question is what Ghana intends to negotiate once it gets a seat at the table.
Beyond the BRICS Label
BRICS is not a conventional economic union or free-trade bloc. It has no constitutive treaty, permanent secretariat or common budget, and its members coordinate across areas including politics and security, economics and finance, and people-to-people cooperation. Major decisions are made by consensus.
That distinction matters.
Membership would give Ghana additional diplomatic access and a platform for cooperation with some of the world’s major emerging economies. It would not automatically deliver factories, infrastructure projects, investment, technology transfers or new export markets.
Those outcomes would have to be negotiated.
And that is where Ghana’s BRICS strategy becomes much more important than the application itself.
What Should Ghana Negotiate For?
If Accra is serious about using BRICS as an economic-development instrument, its negotiating agenda could extend well beyond diplomatic visibility.
1. Better market access for Ghanaian exports
Ghana should seek practical pathways into BRICS markets for products capable of generating greater value domestically.
That means going beyond the traditional export of raw commodities.
Cocoa is the obvious example. Rather than viewing BRICS primarily as another destination for Ghanaian cocoa beans, Accra could pursue partnerships that expand processing, chocolate manufacturing, packaging and related industries inside Ghana.
The same logic applies to minerals, agricultural products, pharmaceuticals, processed foods and manufactured goods.
The objective should be simple: more Ghanaian value created before products leave Ghana.
2. Make the AfCFTA connection a strategic advantage
This may be one of Ghana’s most important cards.
The Secretariat of the African Continental Free Trade Area is headquartered in Accra, giving Ghana an unusual position within Africa’s emerging single-market architecture.
The AfCFTA’s central challenge is moving from negotiated rules to implementation and increasing intra-African trade. Its Secretary-General, Wamkele Mene, said in July 2026 that implementation remains the priority and that intra-African trade exceeded $220 billion in 2024.
Ghana should therefore resist treating BRICS membership simply as a bilateral relationship between Accra and the BRICS capitals.
It can position itself as a gateway between BRICS economies and the African Continental Free Trade Area.
That creates a potentially powerful proposition:
Invest in Ghana, manufacture in Ghana, and use the AfCFTA market as part of the commercial opportunity.
The value would not be Ghana’s population alone. It would be Ghana’s location within a continent-wide market framework.
3. Turn investment interest into industrial capacity
Ghana does not simply need foreign capital.
It needs capital tied to productive capacity.
That means negotiating for investments in manufacturing, agro-processing, pharmaceuticals, renewable energy, logistics, digital infrastructure and other sectors capable of creating jobs and increasing exports.
Accra should be particularly interested in agreements that include local-content requirements, skills development, technology transfer and Ghanaian participation in supply chains.
The question should not simply be:
How much money will you invest?
It should be:
What will Ghana be able to produce five or 10 years after you invest?
4. Pursue development financing strategically
BRICS also has an important financial dimension.
The New Development Bank, created by the BRICS countries, is designed to mobilize resources for infrastructure and sustainable-development projects.
For Ghana, the potential attraction is not simply another source of borrowing.
The strategic question is whether alternative financing relationships can give Accra more options when funding infrastructure, energy, transport, water, technology and industrial projects.
But additional financing is not automatically beneficial.
Ghana would still need to assess the cost of borrowing, repayment risks, project viability, procurement arrangements and the effect on public debt.
BRICS should therefore expand Ghana’s financing choices—not replace financial discipline.
5. Build technology partnerships, not just technology imports
India and China, among others, offer Ghana potential areas for cooperation in digital technology, manufacturing, telecommunications, pharmaceuticals, agriculture and technical education.
But Ghana’s objective should be to develop domestic capabilities rather than become permanently dependent on imported technology.
That means negotiating for training, research partnerships, scholarships, technology transfer, local engineering capacity and participation by Ghanaian companies.
A successful BRICS relationship should leave Ghana with more expertise than it had before the relationship began.
6. Agriculture and food security should be central
Food security is increasingly tied to geopolitics.
Ghana has an opportunity to seek partnerships in agricultural technology, irrigation, mechanization, fertilizer production, food processing, storage and logistics.
The goal should be to move from importing finished or semi-processed food products toward strengthening domestic production and processing.
This would also fit into the broader AfCFTA objective of developing regional value chains.
The Western Question
Perhaps the most delicate part of Ghana’s BRICS strategy will be managing its existing relationships with Western partners.
Ghana does not have to choose between BRICS and the West.
That is one of the most important points in understanding what BRICS membership could mean for Accra.
Ghana has long maintained extensive economic, diplomatic and development relationships with countries and institutions outside BRICS. A strategy of expanding ties with Brazil, Russia, India, China and other emerging economies does not inherently require Ghana to abandon relationships with the United States, European Union, United Kingdom or international financial institutions.
In fact, Ghana could seek to use the competition and diversification of partnerships to increase its negotiating options.
The objective would be strategic diversification, not geopolitical substitution.
But there are also complications.
BRICS includes countries with sharply different political systems, strategic interests and relationships with Western powers. The group also includes Russia, while some BRICS members maintain close relationships with the United States and Europe.
Ghana would therefore need to maintain a foreign policy capable of working across competing geopolitical blocs.
That requires diplomatic discipline.
Accra would need to make clear that economic cooperation with BRICS does not automatically translate into alignment with every member’s foreign-policy position.
Ghana’s Potential Leverage
Ghana may have more to offer BRICS than simply another membership application.
Its democratic credentials, diplomatic relationships across different regions, English-speaking business environment and position in West Africa could give it strategic relevance.
Most importantly, Ghana hosts the AfCFTA Secretariat.
That creates the possibility of positioning Ghana as a meeting point between BRICS economic interests and Africa’s continental market.
The opportunity could be especially significant if Ghana can persuade investors from BRICS economies to use the country not merely as an export destination but as a production and distribution base for the wider African market.
That would make Ghana’s BRICS strategy part of its industrialization strategy.
But Accra Must Avoid the Symbolism Trap
There is a danger in treating BRICS membership itself as an economic achievement.
Membership does not automatically create jobs.
It does not automatically attract factories.
It does not automatically increase exports.
It does not automatically reduce Ghana’s financing costs.
And it does not automatically produce technology transfers.
The BRICS framework itself emphasizes cooperation among major Global South economies and greater participation in global governance, while its expanded membership creates opportunities for broader economic and diplomatic partnerships.
But Ghana’s gains will ultimately depend on what it brings to the negotiating table.
The country will need clear national priorities, strong commercial diplomacy and institutions capable of following agreements from announcement to implementation.
That means ministries, investment agencies, trade negotiators and Ghanaian businesses must be working from the same strategy.
A headline announcing a major investment is not the same thing as a functioning factory.
A memorandum of understanding is not the same thing as a completed project.
A diplomatic meeting is not the same thing as market access.
And a BRICS membership card is not an economic-development plan.
The Bigger Opportunity
Ghana’s BRICS application comes at a moment when the international economic system is becoming more multipolar.
The BRICS group itself describes its expansion as strengthening the ability of Global South countries to engage on issues including global governance reform and sustainable development.
That changing environment could give middle-sized countries such as Ghana greater space to pursue diversified partnerships.
But diplomatic diversification only becomes economically meaningful when it produces tangible outcomes.
For Ghana, those outcomes could include new export markets, industrial investment, infrastructure financing, technology partnerships, stronger agricultural value chains and greater integration between Ghanaian businesses and global supply chains.
The AfCFTA could make the proposition even more powerful.
Instead of presenting Ghana simply as a small West African economy seeking investment, Accra can present itself as a country sitting at the intersection of BRICS capital, African markets and continental trade integration.
That is a much stronger negotiating position.
So, What Will Ghana Negotiate For?
Ghana is asking for a seat at the BRICS table.
The harder question begins after the invitation—or after the application process moves forward.
Will Ghana negotiate for factories or simply investment announcements?
Will it negotiate for technology transfer or simply technology imports?
Will it negotiate for value-added exports rather than continued dependence on raw commodities?
Will it negotiate financing that supports productive infrastructure without creating unsustainable debt?
Will it use its position as the home of the AfCFTA Secretariat to connect BRICS investors to the wider African market?
And can it deepen relationships with emerging powers while maintaining constructive relationships with Western partners?
Those questions matter more than the symbolism of joining another international grouping.
If Ghana gets the strategy right, BRICS could become another instrument in a broader foreign-policy and economic-development agenda.
If it does not, membership could amount largely to another diplomatic badge.
-
 Health & Wellness2 days ago
The Scale Can Lie: Why Lifting Weights May Help You Lose More Fat
-
 Festivals & Events1 day ago
Velukusi Festival: Re-enacting the Ewe Escape to Freedom in Ve-Deme
-
 Taste GH1 day ago
Simple, Nourishing and Rooted in Tradition: Discover Ghana’s Kapala
-
 Fashion & Style2 days ago
Dressing for Your Shape: How Strategic Styling Can Transform Everyday Fashion
-
 Health & Wellness1 day ago
The Weight-Loss Plateau: How Daily Movement and Hidden Calories Can Matter