Business
Ghana Just Legalized Crypto Trading — Here’s What It Means, and What It Doesn’t

Ghana has officially legalised cryptocurrency trading, bringing an end to years of regulatory uncertainty in one of West Africa’s most active digital asset markets.
But while the move brings long-awaited clarity, authorities are making it clear that legalization comes with firm controls — not a free-for-all.
The change follows Parliament’s passage of the Virtual Asset Service Providers (VASP) Bill, which establishes a legal framework for crypto activity and places the sector under direct regulatory oversight for the first time.
From Grey Area to Legal Framework
For years, cryptocurrency use in Ghana existed in a legal grey zone. While not explicitly banned, crypto trading was unregulated, leaving users exposed to fraud and limiting the state’s ability to intervene when problems arose.
That ambiguity ended on December 19, when Bank of Ghana Governor Johnson Asiama announced that virtual asset trading is now lawful nationwide. Speaking at the central bank’s annual Nine Lessons, Carols, and Thanksgiving Service in Accra, Asiama confirmed that individuals will no longer face arrest simply for engaging in crypto-related activity.
However, he firmly stated that legalization does not mean unrestricted freedom.
“This is not an open-ended green light,” Asiama cautioned, underscoring that crypto now falls under the same expectations of governance, supervision, and accountability as other parts of Ghana’s financial system.
What the New Law Actually Does
The VASP Bill gives the Bank of Ghana (BoG) authority to:
- License virtual asset service providers
- Supervise and monitor crypto platforms
- Enforce rules on transparency, compliance, and consumer protection
According to Asiama, the framework is designed to address risks that previously went unchecked, including fraud, money laundering, and threats to financial stability. Under the new regime, crypto companies operating in Ghana must meet regulatory standards similar to those applied to banks and other financial institutions.
In short, crypto is now legal — but regulated.
Why Regulation Became Unavoidable
Ghana’s move reflects realities on the ground. Despite the absence of formal approval in the past, crypto adoption has grown rapidly.
Estimates suggest that around three million adults — roughly 17% of the population — already use digital currencies for savings, payments, remittances, and business transactions. Much of this activity has taken place outside traditional banking channels.
Data from the Web3 Africa Group indicates that crypto transactions in Ghana reached approximately $3 billion between July 2023 and June 2024, highlighting the scale of the market that regulators were previously unable to oversee.
On a regional level, Chainalysis’ 2025 Geography of Cryptocurrency Report ranked Ghana among the top five Sub-Saharan African countries by total crypto value received between July 2024 and June 2025. Across the region, on-chain transaction value exceeded $205 billion, representing a 52% year-on-year increase.
Economic Pressures Add Urgency
Macroeconomic conditions have also accelerated the push for regulation.
The Ghanaian cedi has experienced sharp volatility, appreciating nearly 48% in the past year after losing about 25% in the previous 12 months. At the same time, interest rates remain high at 28%, with inflation at 13.7% as of mid-2025.
For policymakers, crypto activity occurring outside formal banking channels complicates monetary policy, especially in an import-dependent economy where digital assets are increasingly used for cross-border payments.
Officials say tighter oversight will improve visibility into currency flows and help safeguard financial stability — lessons reinforced by governance failures exposed during the 2022 debt crisis.
SEC Warns Influencers as Enforcement Approaches
As the regulatory framework moves toward full enforcement, Ghana’s Securities and Exchange Commission (SEC) has also issued a public warning to celebrities, social media influencers, and digital marketers against promoting cryptocurrencies and other virtual assets without proper authorisation.
The caution comes as the VASP law, now awaiting presidential assent, seeks to introduce comprehensive oversight of virtual asset activities while strengthening anti–money laundering (AML) and counter–terrorism financing (CTF) controls within Ghana’s fast-growing digital finance space.
Speaking at the maiden National Virtual Asset Literacy Programme for Virtual Asset Market Operators, the SEC’s Deputy Director-General in charge of Finance, Mensah Thompson, said the highly volatile nature of virtual assets makes strict regulation of advertising, promotion, and public advocacy essential.
He warned that unchecked endorsements — particularly by high-profile personalities — could expose consumers to significant financial risk, stressing that market education and responsible communication will be critical under the new regulatory regime.
Part of a Broader African Shift
Ghana’s decision aligns with a growing regulatory trend across Africa. South Africa has already licensed dozens of crypto platforms, while Kenya has passed its own VASP bill, now awaiting presidential approval.
Rather than resisting digital assets, African governments are increasingly choosing regulation as a way to balance innovation with control.
The Bottom Line
Ghana’s legalization of crypto trading marks a major policy shift. The move offers legal certainty to millions of users and businesses. But the message from regulators is clear: crypto is welcome, not unchecked.
By placing digital assets under formal supervision, Ghana is betting that clearer rules — rather than prohibition or neglect — are the best way to harness innovation while protecting consumers and the broader economy.





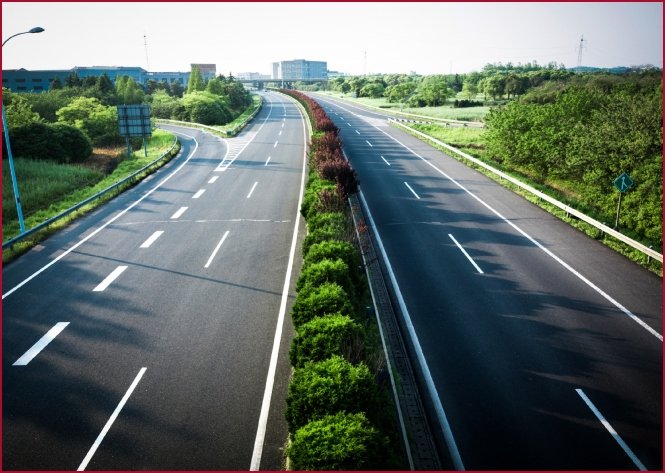
In a bold departure from Ghana’s traditional reliance on external debt, the government has announced that the entire $2 billion needed to finance the Accra-Kumasi Expressway has been secured from domestic sources, with no borrowing involved.
President John Dramani Mahama has confirmed that $2 billion, sourced from taxpayers’ money, has been deposited in a special account at the Bank of Ghana.
“And let me also announce that this is our own money. We have not gone to borrow money from anywhere. This money is the taxpayers’ money,” the President stated at the handover ceremony of the cleared right-of-way on September 14, 2026.
No Borrowing, No Debt Burden
Finance Minister Dr. Cassiel Ato Forson has reinforced this commitment, assuring the nation that “we will not borrow a pesewa for this construction”.
He stated that the full amount required will be ready by December 31, 2026, and reiterated that the government plans to mobilise the required funds entirely from domestic sources, allowing the project to proceed without adding to Ghana’s debt burden.
Timely Payments to Contractors
The funds are lodged in a dedicated account to facilitate timely payments to the contractor throughout the duration of the project.
President Mahama assured that all payment certificates submitted by the contractor would be honoured promptly to prevent delays and ensure the project progresses as scheduled. The project is being managed by a special purpose vehicle, Accra Kumasi Expressway Limited, registered for this purpose.
The GAF Factor in Cost Savings
The government’s domestic financing strategy has been bolstered by significant cost savings from the involvement of the Ghana Armed Forces (GAF) Engineers.
The GAF cleared 175.6 kilometres of the right-of-way in just 19 weeks—beating a 20-week target—at an estimated cost of GH₵10.9 billion, compared with commercial contractor baselines of GH₵15–18 billion. This yielded billions of cedis in net savings.
The $2 billion domestic financing model represents a significant shift in Ghana’s infrastructure funding approach. If successfully executed, it could provide a template for future mega-projects, demonstrating that national development need not come at the cost of mounting external debt.
Business
From Raw Minerals to Luxury Brand: Ghana’s Gold Value-Addition Strategy Gains Global Momentum with UK Showroom
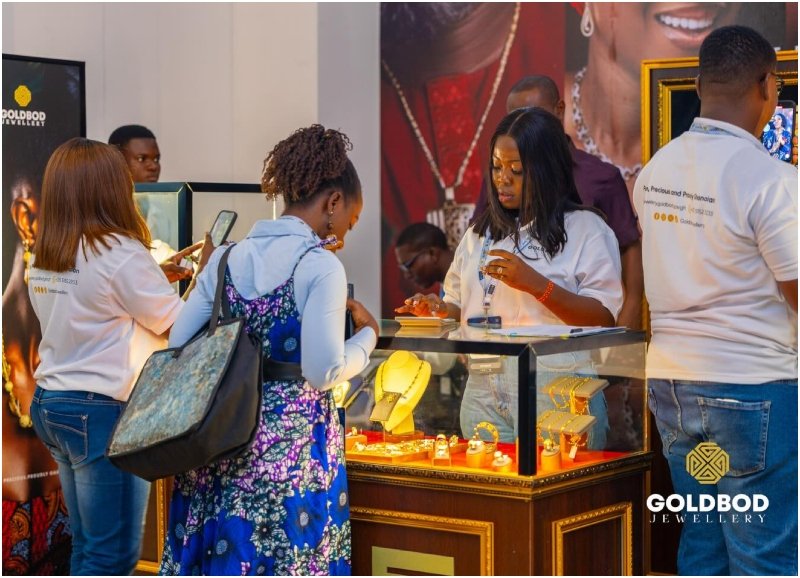
Ghana’s ambition to transform its gold sector from a raw mineral exporter into a competitive player in the global luxury jewelry market has received a significant boost, with indigenous company GOLDBOD Jewellery setting its sights on establishing a flagship showroom in the United Kingdom.
The move, which aligns with the government’s broader strategy of increasing value addition within the gold sector, reflects Ghana’s determination to maximize returns from its mineral resources through local beneficiation, manufacturing and branding initiatives designed to generate employment and enhance export earnings.
Chief Executive Officer of GOLDBOD Jewellery, Gertrude Emefa Donkor, recently paid a courtesy call on Ghana’s High Commissioner to the United Kingdom, Sabah Zita Benson, to present the company’s vision of showcasing premium jewelry and investment-grade gold products crafted from responsibly sourced Ghanaian gold.
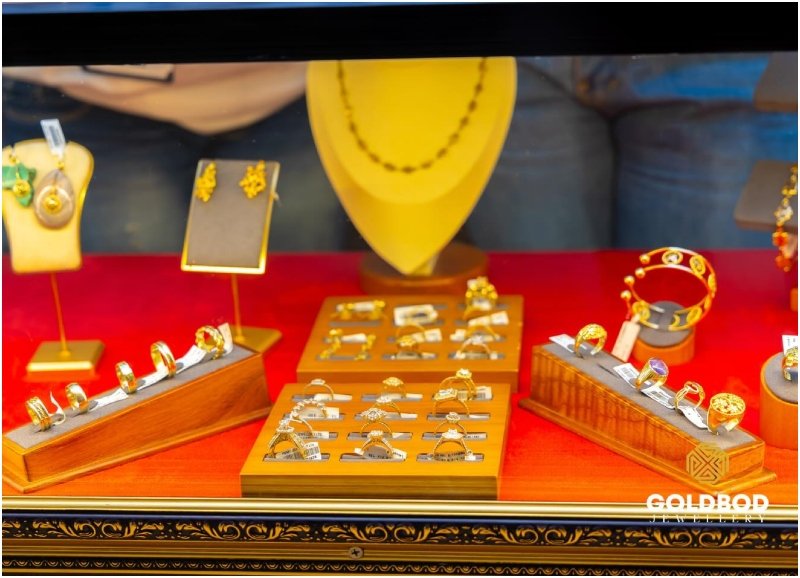
During the discussions, Miss Donkor highlighted the growing demand for the company’s innovative Gold Tablet, revealing that the product sold out during this year’s Ghana Party in the Park in London, one of the largest annual gatherings of the Ghanaian diaspora in Europe. She noted that the overwhelming patronage reflects growing confidence among diaspora communities and international consumers in authenticated Ghanaian gold products.
The planned expansion comes as Ghana, Africa’s leading gold producer, intensifies efforts to move beyond the export of raw minerals and establish a reputation as a trusted source of responsibly produced, value-added gold products.
The strategy is central to the country’s industrialization agenda, which seeks to create jobs, boost foreign exchange earnings and reduce dependence on primary commodity exports.
High Commissioner Benson reaffirmed the Mission’s commitment to supporting Made-in-Ghana products in the UK market, noting that the High Commission continues to collaborate with relevant public institutions, private sector stakeholders and business associations to create opportunities for Ghanaian enterprises seeking to expand internationally.
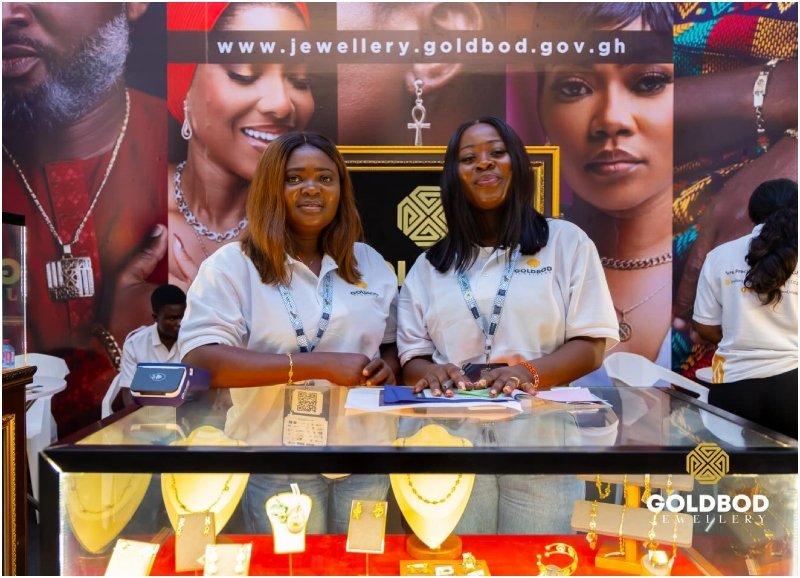
She expressed optimism that the proposed showroom would not only showcase the quality and craftsmanship of Ghanaian jewelry but also reinforce Ghana’s reputation as a trusted source of responsibly produced gold products. She added that initiatives of this nature complement the government’s broader agenda of leveraging trade, investment and economic diplomacy to promote sustainable national development.
The engagement underscores the evolving role of Ghana’s diplomatic missions in advancing economic diplomacy by facilitating market access for Ghanaian businesses and strengthening commercial partnerships abroad. The United Kingdom remains one of Ghana’s key trading partners and a strategic destination for Ghanaian exports, investment and diaspora engagement.
As Africa’s leading gold producer, Ghana has long been a major supplier of raw gold to international markets. However, successive governments have recognised that real economic transformation lies in retaining more value from the mineral through local processing, manufacturing and branding. GOLDBOD Jewellery’s UK expansion represents a tangible example of this vision taking shape on the global stage.
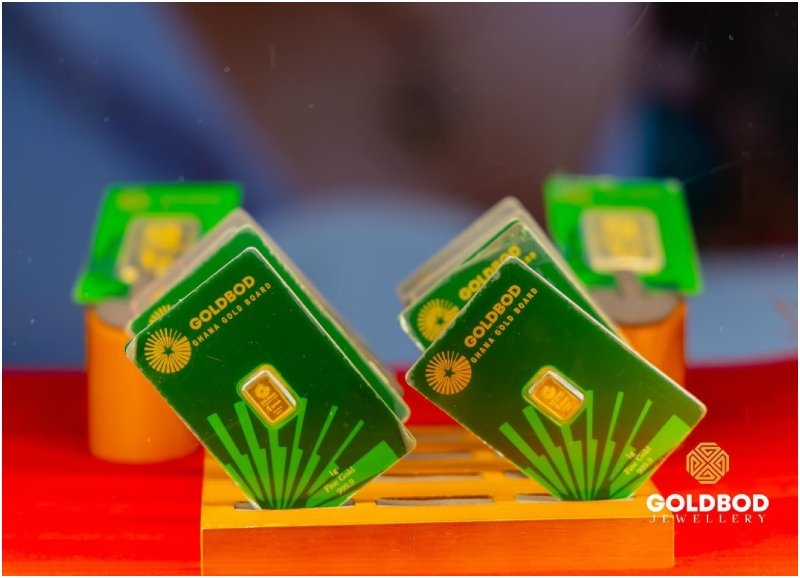
Industry observers note that the success of such initiatives could encourage more Ghanaian companies to explore international markets, particularly in sectors where the country holds a comparative advantage. The diaspora market, in particular, presents a significant opportunity for Ghanaian brands seeking to build consumer confidence and establish a foothold in competitive markets.
The meeting between Miss Donkor and High Commissioner Benson reflects growing collaboration between Ghana’s diplomatic missions and indigenous businesses as the country seeks to strengthen its presence in international markets while advancing industrialization, export diversification and value addition within the mining sector.
With the proposed showroom in the United Kingdom, GOLDBOD Jewellery is positioning itself as a flagship brand for Ghanaian gold, demonstrating that African products can compete at the highest levels of the global luxury market.
The move signals a new chapter in Ghana’s economic story, one in which the nation’s natural resources are transformed into globally recognised brands that tell the story of Ghanaian craftsmanship, quality and innovation.
Business
Ghana Beats the Odds: IMF Approves Final Review, Offering Blueprint for Africa’s Debt-Ridden Economies
Three years after defaulting on its debt, Ghana formally exits the IMF bailout program with a $318 million final disbursement—and a new reform framework that could show other distressed African nations the way forward
The Executive Board of the International Monetary Fund on Monday approved Ghana’s sixth and final review under the Extended Credit Facility (ECF) program, formally concluding the country’s three-year, $3 billion bailout arrangement and unlocking a final disbursement of approximately $318 million.
The Board also approved Ghana’s request for a 36-month Policy Coordination Instrument (PCI), a non-financing arrangement that will guide the country’s economic reforms now that the bailout has ended.
The approval marks the culmination of one of the most dramatic economic turnarounds in recent African history—a recovery that began in the depths of crisis in late 2022, when Ghana defaulted on most of its external debt, inflation topped 54%, and the cedi was in free fall.
“Ghana’s ECF-supported economic program has delivered substantial stabilization gains,” the IMF said in a May statement after reaching a staff-level agreement with the government. “Inflation has declined rapidly, international reserves have been rebuilt, and confidence in the cedi has improved.”
From Default to Credibility
Ghana entered the 36-month ECF arrangement in May 2023 with access to about $3 billion to help restore macroeconomic stability, implement fiscal reforms, and support the country’s debt restructuring program. At the time, the country was in the throes of its worst economic crisis in a generation.
The turnaround has been striking. Inflation has plunged from 54% in December 2022 to just 5.3% in June 2026. Gross international reserves have reached an all-time high of approximately $14.5 billion as of February 2026, providing nearly six months of import cover. The public debt-to-GDP ratio has fallen sharply from a peak of over 80% to 45% by June 2026.
Perhaps most significantly, Ghana’s sovereign credit ratings have improved from restricted default—”junk status”—to ‘B’ with a positive outlook, representing five distinct rating level upgrades.
“Every quantitative performance criterion, but one, set for the final review has been met,” Finance Minister Dr. Cassiel Ato Forson told Parliament while presenting the 2026 Mid-Year Budget Review. He noted that Ghana achieved 10 out of 11 quantitative targets and 8 out of 10 structural benchmarks.
A Blueprint for Africa
For other African nations struggling with debt distress—including Zambia, Ethiopia, and Kenya—Ghana’s trajectory offers a potential roadmap. The country’s success demonstrates that aggressive fiscal consolidation, coupled with credible IMF engagement and good-faith debt restructuring, can restore market confidence within a relatively short timeframe.
The PCI framework that Ghana is now entering is particularly instructive. Unlike the ECF, the PCI does not provide direct funding. Instead, it offers closer policy engagement with the IMF and signals a country’s commitment to reforms, helping to strengthen investor confidence and attract support from development partners.
“Completing the ECF does not mean Ghana walks away from the IMF,” Forson explained. “It means Ghana changes the nature of the relationship.”
The new program will focus on six priority areas: growth-friendly fiscal consolidation, debt sustainability, fiscal transparency and governance, stronger monetary and exchange rate policy frameworks, financial sector stability, and economic diversification.
Forson described the PCI as “a structured, internationally monitored platform through which Ghana commits to a specific set of macroeconomic and structural reform policies, submits to regular independent review, and signals to the world that the discipline of the past eighteen months is not a temporary posture adopted under crisis conditions. It is a permanent feature of how this country will be governed.”
The Work Isn’t Over
Despite the celebration, the IMF has made clear that Ghana’s reform agenda is far from complete. The Fund has urged the government to press ahead with reforms in the energy sector, particularly efforts to improve efficiency at the Electricity Company of Ghana (ECG) through private sector participation.
“Priority should be given to tackling distribution and collection losses at ECG, including advancing private sector participation in the distribution segment,” the IMF stated.
The government has indicated that private sector participation in ECG is expected to commence by early 2027.
The PCI is also designed to help Ghana maintain macroeconomic stability, build resilience against external shocks, address structural imbalances, and support sustainable economic growth. With the global environment remaining uncertain—including potential spillovers from conflicts and volatile commodity prices—sustaining the reform momentum will be critical.
A New Chapter
Monday’s approval formally concludes Ghana’s 16th IMF program since independence. For a country that was written off by many international investors just three years ago, the milestone represents a remarkable redemption story.
“This milestone reflects improved fiscal performance, normalized relations with global creditors, and renewed market confidence,” said Felix Kwakye Ofosu, Minister of State for Government Communications.
Finance Minister Forson has already declared that Ghana does not expect to seek another IMF bailout in the foreseeable future. The country now aims to achieve “Investment Grade” status, a goal that would further lower borrowing costs and unlock long-term institutional investment for critical infrastructure.
For now, however, the immediate priority is clear: cement the gains, stay the course, and prove that Ghana’s recovery is not just a temporary reprieve—but a permanent transformation.