Business
Nigeria Oil Regulator Chief Resigns After Dangote Alleges $5m Corruption Scandal

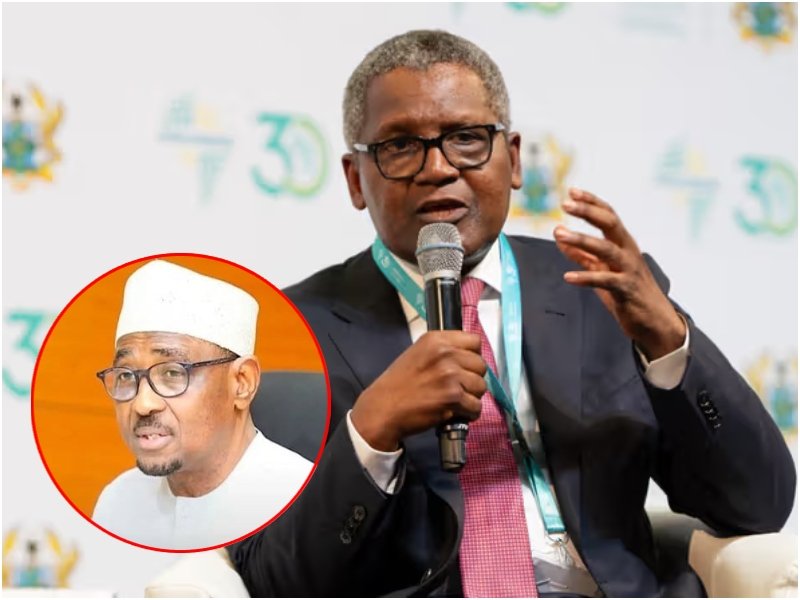
Nigeria’s oil and gas regulatory landscape has been jolted by the resignation of Farouk Ahmed, Chief Executive Officer of the Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA).
His resignation follows explosive corruption allegations by Africa’s richest man, Aliko Dangote.
President Bola Ahmed Tinubu has formally informed the Nigerian Senate of Ahmed’s resignation and has nominated a replacement, signalling swift executive action as public scrutiny intensifies over governance in Africa’s largest oil-producing nation.
The resignation comes just days after Dangote publicly accused the former regulator of living far beyond his lawful means as a public official—claims that have sparked fierce debate in Nigeria and drawn international attention to the country’s energy sector.
Allegations That Rocked the Regulator
According to reports by Business Insider Africa, Dangote alleged during a public briefing in Lagos on December 14 that Ahmed was paying approximately $5 million in school fees for his children at a Swiss institution—an amount widely viewed as inconsistent with public-sector earnings in Nigeria.
Dangote has since filed a formal petition with Nigeria’s Independent Corrupt Practices and Other Related Offences Commission (ICPC), escalating the matter beyond public rhetoric into a legal and institutional test of accountability.
Beyond personal enrichment claims, the billionaire industrialist accused Ahmed of economic sabotage, alleging that regulatory decisions under his leadership favoured fuel importers while undermining local refining efforts—particularly the newly commissioned $20 billion Dangote Refinery, a project central to Nigeria’s ambition to end decades of fuel import dependence.
Ahmed has not publicly responded to the allegations.
Tinubu Moves Quickly to Reassert Control
In a statement issued by presidential spokesperson Bayo Onanuga, President Tinubu nominated Saidu Aliyu Mohammed, a veteran oil and gas executive, as the new CEO of the NMDPRA, urging the Senate to approve the appointment without delay.
Mohammed is a chemical engineering graduate of Ahmadu Bello University, Zaria, and has previously served as Managing Director of the Kaduna Refining and Petrochemical Company and the Nigerian Gas Company. He has also chaired several energy-sector boards and was recently appointed an independent non-executive director at Seplat Energy, one of Nigeria’s largest listed oil producers.
Wider Shake-Up in Nigeria’s Energy Oversight
The changes extend beyond the downstream sector. Tinubu has also requested Senate confirmation of Oritsemeyiwa Amanorisewo Eyesan as Chief Executive Officer of the Nigerian Upstream Petroleum Regulatory Commission (NUPRC), following the resignation of its former head, Gbenga Komolafe.
Eyesan, an economics graduate of the University of Benin, spent nearly 33 years at the Nigerian National Petroleum Corporation (NNPC) and its subsidiaries, retiring as Executive Vice President for Upstream operations after holding senior roles in strategy, asset management and corporate planning.
Both outgoing regulators were appointed in 2021 by former President Muhammadu Buhari under the Petroleum Industry Act (PIA)—a landmark reform law aimed at modernising Nigeria’s oil governance, improving transparency and attracting foreign investment.
Implications Beyond Nigeria
For observers across West Africa, including Ghana, the episode highlights familiar tensions in resource governance: the clash between reform ambitions and entrenched institutional weaknesses.
Nigeria’s oil sector accounts for the bulk of its foreign exchange earnings, making credibility, regulatory integrity and investor confidence critical not just domestically, but for the wider African energy market.
For global investors and policymakers, the unfolding scandal underscores both the promise and fragility of Nigeria’s reform agenda. Much now depends on how authorities handle Dangote’s allegations and whether investigations lead to accountability—or deepen scepticism.
As the Senate considers the nominations, attention remains fixed on Abuja, where the response to this crisis may shape the future of Nigeria’s energy sector—and Africa’s most consequential refinery project—for years to come.






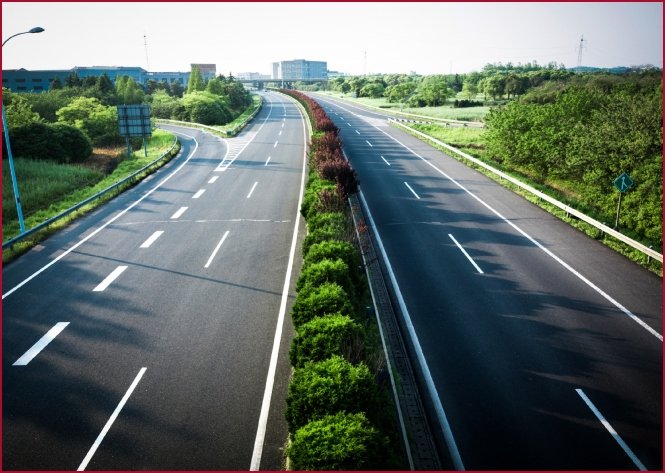
In a bold departure from Ghana’s traditional reliance on external debt, the government has announced that the entire $2 billion needed to finance the Accra-Kumasi Expressway has been secured from domestic sources, with no borrowing involved.
President John Dramani Mahama has confirmed that $2 billion, sourced from taxpayers’ money, has been deposited in a special account at the Bank of Ghana.
“And let me also announce that this is our own money. We have not gone to borrow money from anywhere. This money is the taxpayers’ money,” the President stated at the handover ceremony of the cleared right-of-way on September 14, 2026.
No Borrowing, No Debt Burden
Finance Minister Dr. Cassiel Ato Forson has reinforced this commitment, assuring the nation that “we will not borrow a pesewa for this construction”.
He stated that the full amount required will be ready by December 31, 2026, and reiterated that the government plans to mobilise the required funds entirely from domestic sources, allowing the project to proceed without adding to Ghana’s debt burden.
Timely Payments to Contractors
The funds are lodged in a dedicated account to facilitate timely payments to the contractor throughout the duration of the project.
President Mahama assured that all payment certificates submitted by the contractor would be honoured promptly to prevent delays and ensure the project progresses as scheduled. The project is being managed by a special purpose vehicle, Accra Kumasi Expressway Limited, registered for this purpose.
The GAF Factor in Cost Savings
The government’s domestic financing strategy has been bolstered by significant cost savings from the involvement of the Ghana Armed Forces (GAF) Engineers.
The GAF cleared 175.6 kilometres of the right-of-way in just 19 weeks—beating a 20-week target—at an estimated cost of GH₵10.9 billion, compared with commercial contractor baselines of GH₵15–18 billion. This yielded billions of cedis in net savings.
The $2 billion domestic financing model represents a significant shift in Ghana’s infrastructure funding approach. If successfully executed, it could provide a template for future mega-projects, demonstrating that national development need not come at the cost of mounting external debt.
Business
From Raw Minerals to Luxury Brand: Ghana’s Gold Value-Addition Strategy Gains Global Momentum with UK Showroom
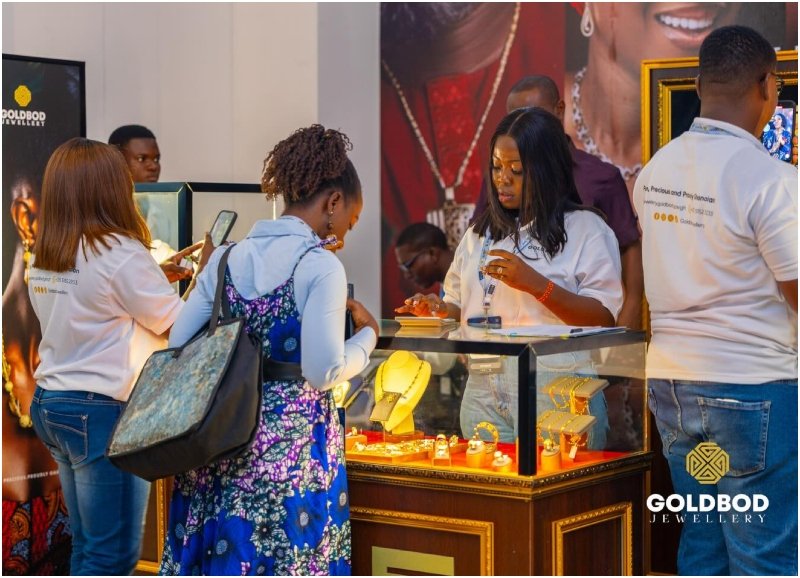
Ghana’s ambition to transform its gold sector from a raw mineral exporter into a competitive player in the global luxury jewelry market has received a significant boost, with indigenous company GOLDBOD Jewellery setting its sights on establishing a flagship showroom in the United Kingdom.
The move, which aligns with the government’s broader strategy of increasing value addition within the gold sector, reflects Ghana’s determination to maximize returns from its mineral resources through local beneficiation, manufacturing and branding initiatives designed to generate employment and enhance export earnings.
Chief Executive Officer of GOLDBOD Jewellery, Gertrude Emefa Donkor, recently paid a courtesy call on Ghana’s High Commissioner to the United Kingdom, Sabah Zita Benson, to present the company’s vision of showcasing premium jewelry and investment-grade gold products crafted from responsibly sourced Ghanaian gold.
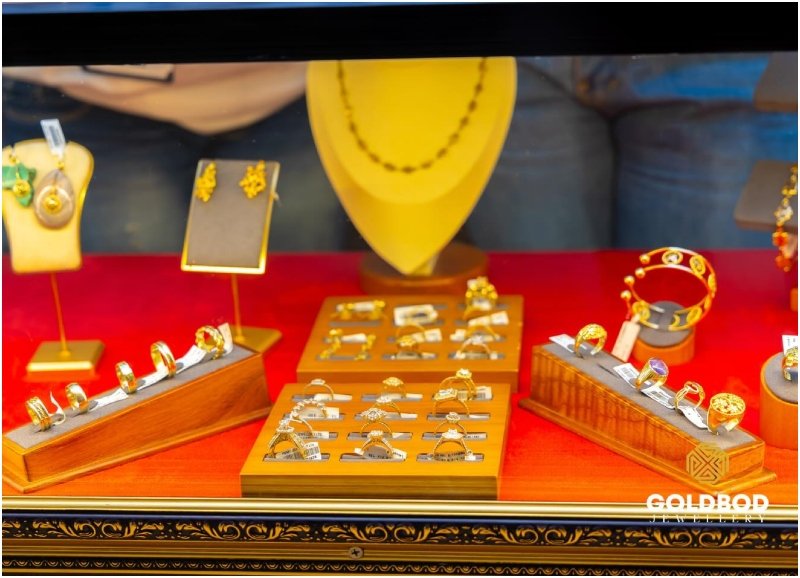
During the discussions, Miss Donkor highlighted the growing demand for the company’s innovative Gold Tablet, revealing that the product sold out during this year’s Ghana Party in the Park in London, one of the largest annual gatherings of the Ghanaian diaspora in Europe. She noted that the overwhelming patronage reflects growing confidence among diaspora communities and international consumers in authenticated Ghanaian gold products.
The planned expansion comes as Ghana, Africa’s leading gold producer, intensifies efforts to move beyond the export of raw minerals and establish a reputation as a trusted source of responsibly produced, value-added gold products.
The strategy is central to the country’s industrialization agenda, which seeks to create jobs, boost foreign exchange earnings and reduce dependence on primary commodity exports.
High Commissioner Benson reaffirmed the Mission’s commitment to supporting Made-in-Ghana products in the UK market, noting that the High Commission continues to collaborate with relevant public institutions, private sector stakeholders and business associations to create opportunities for Ghanaian enterprises seeking to expand internationally.
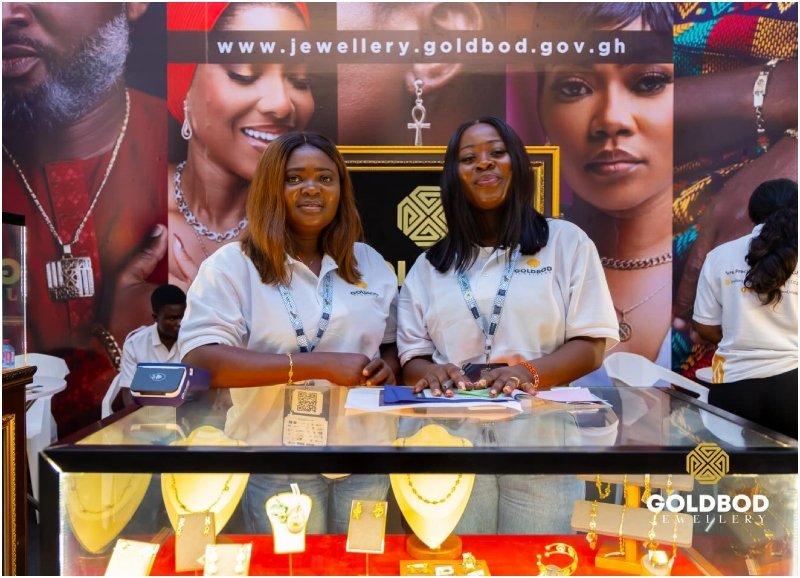
She expressed optimism that the proposed showroom would not only showcase the quality and craftsmanship of Ghanaian jewelry but also reinforce Ghana’s reputation as a trusted source of responsibly produced gold products. She added that initiatives of this nature complement the government’s broader agenda of leveraging trade, investment and economic diplomacy to promote sustainable national development.
The engagement underscores the evolving role of Ghana’s diplomatic missions in advancing economic diplomacy by facilitating market access for Ghanaian businesses and strengthening commercial partnerships abroad. The United Kingdom remains one of Ghana’s key trading partners and a strategic destination for Ghanaian exports, investment and diaspora engagement.
As Africa’s leading gold producer, Ghana has long been a major supplier of raw gold to international markets. However, successive governments have recognised that real economic transformation lies in retaining more value from the mineral through local processing, manufacturing and branding. GOLDBOD Jewellery’s UK expansion represents a tangible example of this vision taking shape on the global stage.
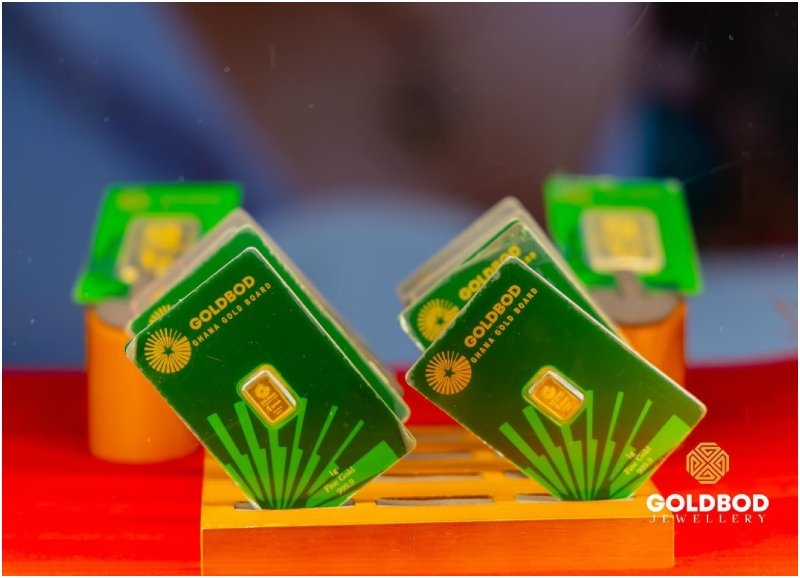
Industry observers note that the success of such initiatives could encourage more Ghanaian companies to explore international markets, particularly in sectors where the country holds a comparative advantage. The diaspora market, in particular, presents a significant opportunity for Ghanaian brands seeking to build consumer confidence and establish a foothold in competitive markets.
The meeting between Miss Donkor and High Commissioner Benson reflects growing collaboration between Ghana’s diplomatic missions and indigenous businesses as the country seeks to strengthen its presence in international markets while advancing industrialization, export diversification and value addition within the mining sector.
With the proposed showroom in the United Kingdom, GOLDBOD Jewellery is positioning itself as a flagship brand for Ghanaian gold, demonstrating that African products can compete at the highest levels of the global luxury market.
The move signals a new chapter in Ghana’s economic story, one in which the nation’s natural resources are transformed into globally recognised brands that tell the story of Ghanaian craftsmanship, quality and innovation.
Business
Ghana Beats the Odds: IMF Approves Final Review, Offering Blueprint for Africa’s Debt-Ridden Economies
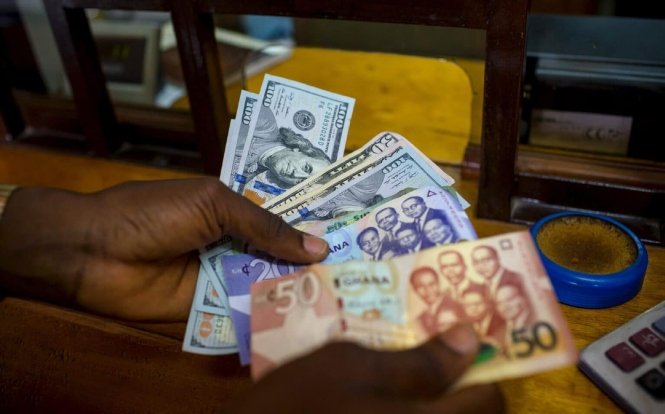
Three years after defaulting on its debt, Ghana formally exits the IMF bailout program with a $318 million final disbursement—and a new reform framework that could show other distressed African nations the way forward
The Executive Board of the International Monetary Fund on Monday approved Ghana’s sixth and final review under the Extended Credit Facility (ECF) program, formally concluding the country’s three-year, $3 billion bailout arrangement and unlocking a final disbursement of approximately $318 million.
The Board also approved Ghana’s request for a 36-month Policy Coordination Instrument (PCI), a non-financing arrangement that will guide the country’s economic reforms now that the bailout has ended.
The approval marks the culmination of one of the most dramatic economic turnarounds in recent African history—a recovery that began in the depths of crisis in late 2022, when Ghana defaulted on most of its external debt, inflation topped 54%, and the cedi was in free fall.
“Ghana’s ECF-supported economic program has delivered substantial stabilization gains,” the IMF said in a May statement after reaching a staff-level agreement with the government. “Inflation has declined rapidly, international reserves have been rebuilt, and confidence in the cedi has improved.”
From Default to Credibility
Ghana entered the 36-month ECF arrangement in May 2023 with access to about $3 billion to help restore macroeconomic stability, implement fiscal reforms, and support the country’s debt restructuring program. At the time, the country was in the throes of its worst economic crisis in a generation.
The turnaround has been striking. Inflation has plunged from 54% in December 2022 to just 5.3% in June 2026. Gross international reserves have reached an all-time high of approximately $14.5 billion as of February 2026, providing nearly six months of import cover. The public debt-to-GDP ratio has fallen sharply from a peak of over 80% to 45% by June 2026.
Perhaps most significantly, Ghana’s sovereign credit ratings have improved from restricted default—”junk status”—to ‘B’ with a positive outlook, representing five distinct rating level upgrades.
“Every quantitative performance criterion, but one, set for the final review has been met,” Finance Minister Dr. Cassiel Ato Forson told Parliament while presenting the 2026 Mid-Year Budget Review. He noted that Ghana achieved 10 out of 11 quantitative targets and 8 out of 10 structural benchmarks.
A Blueprint for Africa
For other African nations struggling with debt distress—including Zambia, Ethiopia, and Kenya—Ghana’s trajectory offers a potential roadmap. The country’s success demonstrates that aggressive fiscal consolidation, coupled with credible IMF engagement and good-faith debt restructuring, can restore market confidence within a relatively short timeframe.
The PCI framework that Ghana is now entering is particularly instructive. Unlike the ECF, the PCI does not provide direct funding. Instead, it offers closer policy engagement with the IMF and signals a country’s commitment to reforms, helping to strengthen investor confidence and attract support from development partners.
“Completing the ECF does not mean Ghana walks away from the IMF,” Forson explained. “It means Ghana changes the nature of the relationship.”
The new program will focus on six priority areas: growth-friendly fiscal consolidation, debt sustainability, fiscal transparency and governance, stronger monetary and exchange rate policy frameworks, financial sector stability, and economic diversification.
Forson described the PCI as “a structured, internationally monitored platform through which Ghana commits to a specific set of macroeconomic and structural reform policies, submits to regular independent review, and signals to the world that the discipline of the past eighteen months is not a temporary posture adopted under crisis conditions. It is a permanent feature of how this country will be governed.”
The Work Isn’t Over
Despite the celebration, the IMF has made clear that Ghana’s reform agenda is far from complete. The Fund has urged the government to press ahead with reforms in the energy sector, particularly efforts to improve efficiency at the Electricity Company of Ghana (ECG) through private sector participation.
“Priority should be given to tackling distribution and collection losses at ECG, including advancing private sector participation in the distribution segment,” the IMF stated.
The government has indicated that private sector participation in ECG is expected to commence by early 2027.
The PCI is also designed to help Ghana maintain macroeconomic stability, build resilience against external shocks, address structural imbalances, and support sustainable economic growth. With the global environment remaining uncertain—including potential spillovers from conflicts and volatile commodity prices—sustaining the reform momentum will be critical.
A New Chapter
Monday’s approval formally concludes Ghana’s 16th IMF program since independence. For a country that was written off by many international investors just three years ago, the milestone represents a remarkable redemption story.
“This milestone reflects improved fiscal performance, normalized relations with global creditors, and renewed market confidence,” said Felix Kwakye Ofosu, Minister of State for Government Communications.
Finance Minister Forson has already declared that Ghana does not expect to seek another IMF bailout in the foreseeable future. The country now aims to achieve “Investment Grade” status, a goal that would further lower borrowing costs and unlock long-term institutional investment for critical infrastructure.
For now, however, the immediate priority is clear: cement the gains, stay the course, and prove that Ghana’s recovery is not just a temporary reprieve—but a permanent transformation.